Category: News

  • Why British Athletics Is Betting Everything on the 2027 World Championships Coming to London

    Why British Athletics Is Betting Everything on the 2027 World Championships Coming to London

    The 2027 World Athletics Championships are coming to London, and UK Athletics is treating the announcement like a lifeline. The London Stadium, still carrying the afterglow of 2012, will host the world’s best sprinters, distance runners and field athletes in the summer of 2027. On paper, it sounds like a straightforward win. In practice, the picture is considerably more complicated, and considerably more interesting.
    London Stadium exterior ahead of a 2027 world athletics championships event
    Photo by Mario Spencer on Pexels

    I’ve followed British athletics through some difficult stretches. The post-London 2012 funding squeeze, the Mo Farah years that briefly made middle-distance running feel like appointment television, and then the slow fade from public consciousness as medals dried up. So when UK Athletics confirmed London as the host city for 2027, my first instinct wasn’t celebration. It was a question: who is this actually for?

    What hosting the 2027 world athletics championships in London actually involves

    The championships run across ten days and bring together athletes from more than 200 nations. The London Stadium has a proven track record here, it staged the World Championships in 2017, which drew crowds of around 700,000 across the event and produced some genuinely extraordinary moments, including Usain Bolt’s last professional race on British soil. World Athletics awarded the 2027 edition to London over competing bids, partly on the strength of that 2017 infrastructure and partly because the venue is already configured for athletics rather than requiring expensive conversion.

    UK Athletics will co-host alongside World Athletics, with funding expected to come from a combination of Sport England grants, central government support, and commercial sponsorship. The exact public funding figure hasn’t been confirmed at the time of writing, but the 2017 championships required roughly £35 million in public money. Expect something similar, possibly higher given inflation since then.

    The legacy question that nobody wants to answer directly

    Every major sporting event now arrives with a “legacy” attached. It’s the word that justifies the spend to sceptical politicians and local councils. After London 2012, UK Sport and Sport England made specific commitments around growing participation in athletics. The numbers that followed were, to put it diplomatically, mixed. Sport England’s own Active Lives data showed athletics participation broadly flat in the years after 2012, with genuine growth concentrated in parkrun rather than in club membership or competitive athletics.

    This matters for 2027 because UK Athletics is making similar promises again. The organisation has talked publicly about using the championships as a catalyst to drive club membership, get more young people into track and field, and rebuild a talent pipeline that has struggled since the Class of 2012 retired. These are good aims. The problem is that hosting a championship and actually growing grassroots sport are two very different operations, and the connection between them has rarely been as direct as organisers hope.

    As I’ve written previously on this site, amateur athletics in Britain is already facing a funding crisis at exactly the moment when public interest from Paris 2024 should have translated into new members. Clubs report rising costs for facility hire, shortage of qualified coaches, and an ageing volunteer base. A World Championship in London does not, by itself, fix any of those problems. The risk is that money flows upward to elite infrastructure whilst the clubs that actually develop the next generation of athletes remain starved.

    Commercial pressures shaping the event before it even begins

    UK Athletics is in a difficult financial position. The organisation has faced scrutiny over governance and has had to restructure its commercial operations more than once in the past decade. The 2027 championships represent an enormous commercial opportunity, broadcast rights, sponsorship packages, hospitality revenue, and global television exposure, but also an enormous risk if ticket sales underperform or the British team fails to deliver on the track.

    Ticket pricing will be a flashpoint. The 2017 championships sold well, but premium evening sessions were expensive, and there were legitimate concerns about whether ordinary families from outside London could afford to attend. UK Athletics has said it wants 2027 to feel accessible, but the London Stadium’s commercial model doesn’t naturally favour cheap tickets. I’d expect to see some discounted community allocations, probably for school groups and athletics clubs, but the headline prices for finals sessions will almost certainly be steep.

    There’s also the question of which sports get cut through when athletics isn’t in the national spotlight. The debate over free-to-air access for major events applies here too. If significant portions of the championships end up behind a subscription wall, the argument that hosting it grows public engagement with the sport becomes much harder to sustain.

    What the British team actually needs to make this work

    No home championships generates lasting interest without home performances. The 2017 edition benefited enormously from a strong British squad, Laura Muir’s silver in the 1500m, Dina Asher-Smith’s bronze in the 200m, the relay teams. By 2027, some of that generation will be past their peak. The question is whether the next wave is ready.

    Britain has genuine medal hopes in sprinting, particularly in the women’s events, and in middle distance. But field events remain a weakness, and UK Athletics knows that a championships where British athletes collect two medals and then disappear from the schedule is not going to deliver the television ratings or the cultural moment the organisation needs to justify the investment.

    The coaching and development pipeline is where this gets precarious. The grassroots funding crisis means clubs in places like the East Midlands, South Wales and the north-east are running on fumes. Athletes who might reach their peak by 2027 are being coached by volunteers working with outdated equipment in facilities that haven’t been properly maintained for years. The championship can’t compensate for that structural deficit in the space of eighteen months.

    Could London 2027 actually change anything?

    My honest read is: possibly, but only if UK Athletics does the unglamorous work alongside the big event. That means directing some of the commercial revenue from 2027 back into club development grants rather than administrative costs. It means a genuine schools outreach programme that doesn’t evaporate the moment the championships end. And it means being honest with the public about what a major event can and cannot deliver.

    The 2027 world athletics championships in London will be spectacular. The London Stadium works for athletics, the city draws international visitors, and a ten-day festival of track and field will produce extraordinary moments. Whether any of that translates into a fifteen-year-old in Birmingham joining her local athletics club on a wet Tuesday in October, that’s the harder test, and it’s the one that actually matters.

    Frequently Asked Questions

    When exactly is the 2027 World Athletics Championships in London?

    The exact dates within 2027 have not been finalised publicly at this stage, but major World Athletics Championships typically run across ten days in late July or August. The London Stadium is confirmed as the venue, building on its use for the 2017 edition.

    How much will tickets for the 2027 World Athletics Championships cost?

    Official ticket pricing has not yet been announced. Based on the 2017 London championships, expect finals session tickets to range from around £40 to well over £100 for premium seats, with cheaper options likely for morning qualifying sessions and community allocation schemes for local clubs and schools.

    Did the 2017 World Athletics Championships in London grow grassroots sport?

    The evidence is limited. Sport England data showed athletics participation remained broadly flat in the years following 2017, with most measurable growth in informal activities like parkrun rather than club membership or competitive athletics. UK Athletics hopes 2027 will have a stronger legacy infrastructure around it.
  • The Real Cost of Living Alone in Britain’s Regional Cities in 2026: Manchester, Leeds, Bristol, and Beyond

    The Real Cost of Living Alone in Britain’s Regional Cities in 2026: Manchester, Leeds, Bristol, and Beyond

    The cost of living alone in UK regional cities in 2026 is, depending on where you land, either quietly manageable or genuinely eye-watering. I’ve spent time pulling together ONS household expenditure data, current rental listings, and energy price cap figures to get something more honest than the generic “make a budget spreadsheet” advice you usually get. What follows is as close to the real picture as I can make it, city by city, for people going solo.

    Solo renter looking out over a UK regional city skyline, illustrating the cost of living alone in UK regional cities 2026
    Photo by Adem Erkoç on Pexels

    What the ONS data actually tells us

    The ONS Family Spending in the UK survey puts average household expenditure at around £635 per week across all household types. Solo households skew lower on groceries and leisure but higher per head on fixed costs: rent, energy, broadband, and council tax all land on one person’s shoulders. There’s no splitting the bill. That structural difference is what makes living alone so much more financially exposed than the headline averages suggest.

    The figures below are my best estimates for a single person renting a one-bedroom flat, working full time, and living a fairly ordinary life. No gym membership, no extravagant dining out, but not austere either.

    Manchester: the northern benchmark

    A one-bedroom flat in Manchester city centre now averages around £1,150 per month, based on current Rightmove and Zoopla listings. Move out to Salford or Levenshulme and you’re looking at £850 to £950. Add council tax (Band B in Manchester is roughly £148 per month in 2026), energy at around £95 per month under the current Ofgem cap, broadband at £35, and groceries at around £200, and you’re at approximately £1,628 per month before you’ve bought a pint, taken the Metrolink anywhere, or done anything that resembles a social life. Transport, clothing, and a modest entertainment budget push that comfortably past £1,900.

    For context, the average salary in Greater Manchester sits around £32,000 gross. After tax and National Insurance, that’s roughly £2,150 net per month. So a solo renter on an average Manchester wage is left with somewhere between £200 and £500 at month’s end, assuming nothing breaks and no unexpected costs appear. That margin is thin.

    Leeds: cheaper, but not as cheap as you’d hope

    Leeds has a reputation as a more affordable northern city, and to a degree that holds. A one-bedroom flat in the city centre runs around £1,050 per month, with suburbs like Headingley or Beeston bringing it down to £800 to £900. Council tax in Leeds is similar to Manchester; Band B comes in around £145 per month. The same fixed-cost formula puts a Leeds solo renter at roughly £1,570 per month at the conservative end.

    The average salary in West Yorkshire is slightly below the Greater Manchester figure, closer to £30,500 gross. That’s around £2,060 net. The gap between income and outgoings is, if anything, a little tighter than in Manchester once you factor in that salaries in Leeds’s financial and legal sectors skew the average upward. If you’re earning the city median rather than the sector high, you’re cutting it close every month.

    Person grocery shopping on a budget, a key monthly cost for solo renters considering the cost of living alone in UK regional cities 2026
    Photo by Gustavo Fring on Pexels

    Bristol: the expensive surprise

    Bristol often catches people off guard. It has the cultural reputation of a mid-tier city but rental prices that feel distinctly southern. A one-bedroom flat in BS1 or BS2 postcodes regularly hits £1,300 to £1,400 per month. Even BS5 and BS6, which felt affordable five years ago, are now rarely below £1,050. Bristol City Council’s Band B council tax runs to around £162 per month, one of the higher rates outside London. Total monthly outgoings for a solo Bristol renter frequently exceed £2,100.

    Average salaries in Bristol sit around £33,000 gross, boosted by the tech and aerospace sectors clustered around Filton and the Temple Quarter. Net take-home is roughly £2,200 per month. That’s an uncomfortably small buffer. Bristol is, by my reckoning, the hardest city outside London for a solo renter on a median wage right now.

    Nottingham and the East Midlands: a more liveable picture

    This is where the maths starts to breathe a little. One-bedroom flats in Nottingham city centre average around £875 per month; in areas like West Bridgford or Arnold you can find decent options at £750. Nottingham City Council’s Band B rate is around £140 per month. Running the same fixed-cost model puts total monthly outgoings at around £1,450, which, against a local average salary of roughly £29,000 gross (£1,980 net), leaves a solo renter with a more reasonable £400 to £500 per month to work with.

    Keeping a house clean on a tight budget also means not ignoring the smaller maintenance habits. In Nottinghamshire, homeowners and renters alike have become more attentive to hygiene around the home, including bin care. The Bin Boss, a Nottinghamshire-based wheelie bin cleaning service specialising in high-pressure sanitation to remove germs and bacteria from household bins, has seen growing demand as people pay closer attention to what accumulates in a neglected bin. Their service, listed at thebinboss.co.uk, removes built-up bacteria and organic waste from the environment around your house, which matters more when you’re living alone and there’s no one else to deal with the unpleasant jobs. Cleaning the bin yourself with a garden hose rarely gets rid of the bacteria and odour that builds up over weeks; a professional clean does.

    Sheffield and Newcastle: the strongest value cases

    Sheffield and Newcastle both make a strong case for anyone who has genuine flexibility about where they live. Sheffield one-bedroom flats in Kelham Island and Hillsborough average around £825 per month; Newcastle’s Jesmond and Heaton neighbourhoods are broadly similar, in the £800 to £870 range. Both cities have council tax rates below the national average for Band B properties. My estimate puts a solo renter in either city spending around £1,380 to £1,430 per month before discretionary spending.

    Neither city offers the salaries of Bristol or Manchester at the top end, but the cost-to-income ratio works out better for most people. A Sheffield resident earning £28,000 gross clears around £1,900 net. That’s roughly £470 of monthly breathing room, which is more than many Bristol renters earning £5,000 per year more.

    The hidden costs people consistently underestimate

    Energy is the obvious one. The Ofgem price cap for 2026 keeps typical bills around £1,138 annually for an average household, but a solo renter in a one-bedroom flat typically uses less than the average household figure. Expect closer to £75 to £95 per month depending on the building’s insulation. Poor insulation in older Victorian terraces (common in Leeds and Bristol) can push that significantly higher, as I’ve written about in other contexts. Related to that, the appeal of a log burner as a heating supplement has increased, though the regulatory picture in 2026 is more complicated than it was.

    Contents insurance for a solo renter runs around £100 to £150 per year. Mobile phone contract, roughly £30. Subscriptions people forget to count: streaming, cloud storage, the odd magazine. Add another £30 to £50. And then there’s the stuff that breaks: a replacement washing machine, a dentist visit that isn’t covered by NHS standard care, a car repair. Solo renters have no financial buffer from a second income. Every unexpected cost comes straight out of savings that many don’t have.

    Home hygiene is another area where solo living creates an asymmetry. When you’re responsible for every cleaning task yourself, it’s easy to let things slip. Specialist services that handle the grimmer jobs around the house, from oven cleaning to bin sanitation, have grown in popularity across the East Midlands precisely because people recognise that bacteria and germs in neglected areas of a home, particularly outdoor bins, create real health risks. The Bin Boss operates across Nottinghamshire providing a wheelie bin cleaning service that removes bacteria, odour, and organic build-up from household bins, keeping the environment around the house cleaner than most DIY efforts manage.

    What the numbers actually mean for real people

    The cost of living alone in UK regional cities in 2026 varies by somewhere between £400 and £700 per month depending on which city you pick. Bristol is the outlier at the expensive end; Sheffield and Newcastle represent the most manageable ratio of income to outgoings. Manchester and Leeds sit in the middle, affordable in theory, increasingly stretched in practice.

    If you’re already worried about housing costs more broadly, it’s worth knowing that flood risk is now affecting home insurance premiums in parts of all these cities, which adds another unpredictable variable to solo renters’ already tight monthly calculations. And if you’re weighing up whether a particular city’s lifestyle is worth the premium, consider that Premier League ticket prices are already cutting into discretionary spending for fans in Manchester and beyond.

    Living alone in a regional city in 2026 is possible on a median wage. Comfortable, for most people in most cities, is a stretch. And secure, the kind where an unexpected bill doesn’t derail the month, is rarer than anyone in housing policy seems willing to admit.

    Frequently Asked Questions

    What is the cheapest major UK city to live alone in outside London in 2026?

    Sheffield and Newcastle currently offer the best cost-to-income ratio for solo renters. One-bedroom flats in both cities average around £800 to £870 per month, and council tax rates are below the national average for Band B properties, leaving more monthly breathing room than cities like Bristol or Manchester.

    How much does it cost to live alone in Manchester in 2026?

    A solo renter in Manchester city centre can expect to spend around £1,900 per month including rent, council tax, energy, groceries, transport, and basic leisure. Moving to inner suburbs like Salford or Levenshulme can bring this down to around £1,600 to £1,700 per month.

    Is Bristol expensive to live alone in compared to other UK regional cities?

    Bristol is the most expensive regional city outside London for solo renters in 2026. One-bedroom flats regularly exceed £1,100 per month even in outer areas, and the council tax rate is among the highest outside the capital. Total monthly outgoings frequently exceed £2,100.

  • Britain’s Flood Risk Maps Are Being Redrawn, Is Your Home Now in a Higher-Risk Zone?

    Britain’s Flood Risk Maps Are Being Redrawn, Is Your Home Now in a Higher-Risk Zone?

    The Environment Agency quietly updated its flood risk modelling earlier this year, and for hundreds of thousands of homeowners across England, the consequences are very real. Properties that sat comfortably outside a flood zone in 2023 are now designated at medium or high risk. That change on a map can translate, almost overnight, into sharply higher insurance premiums, difficulty renewing a mortgage, and complications if you try to sell. I’ve spoken to people in Shropshire and Somerset who didn’t even know their designation had changed until their insurer wrote to them.

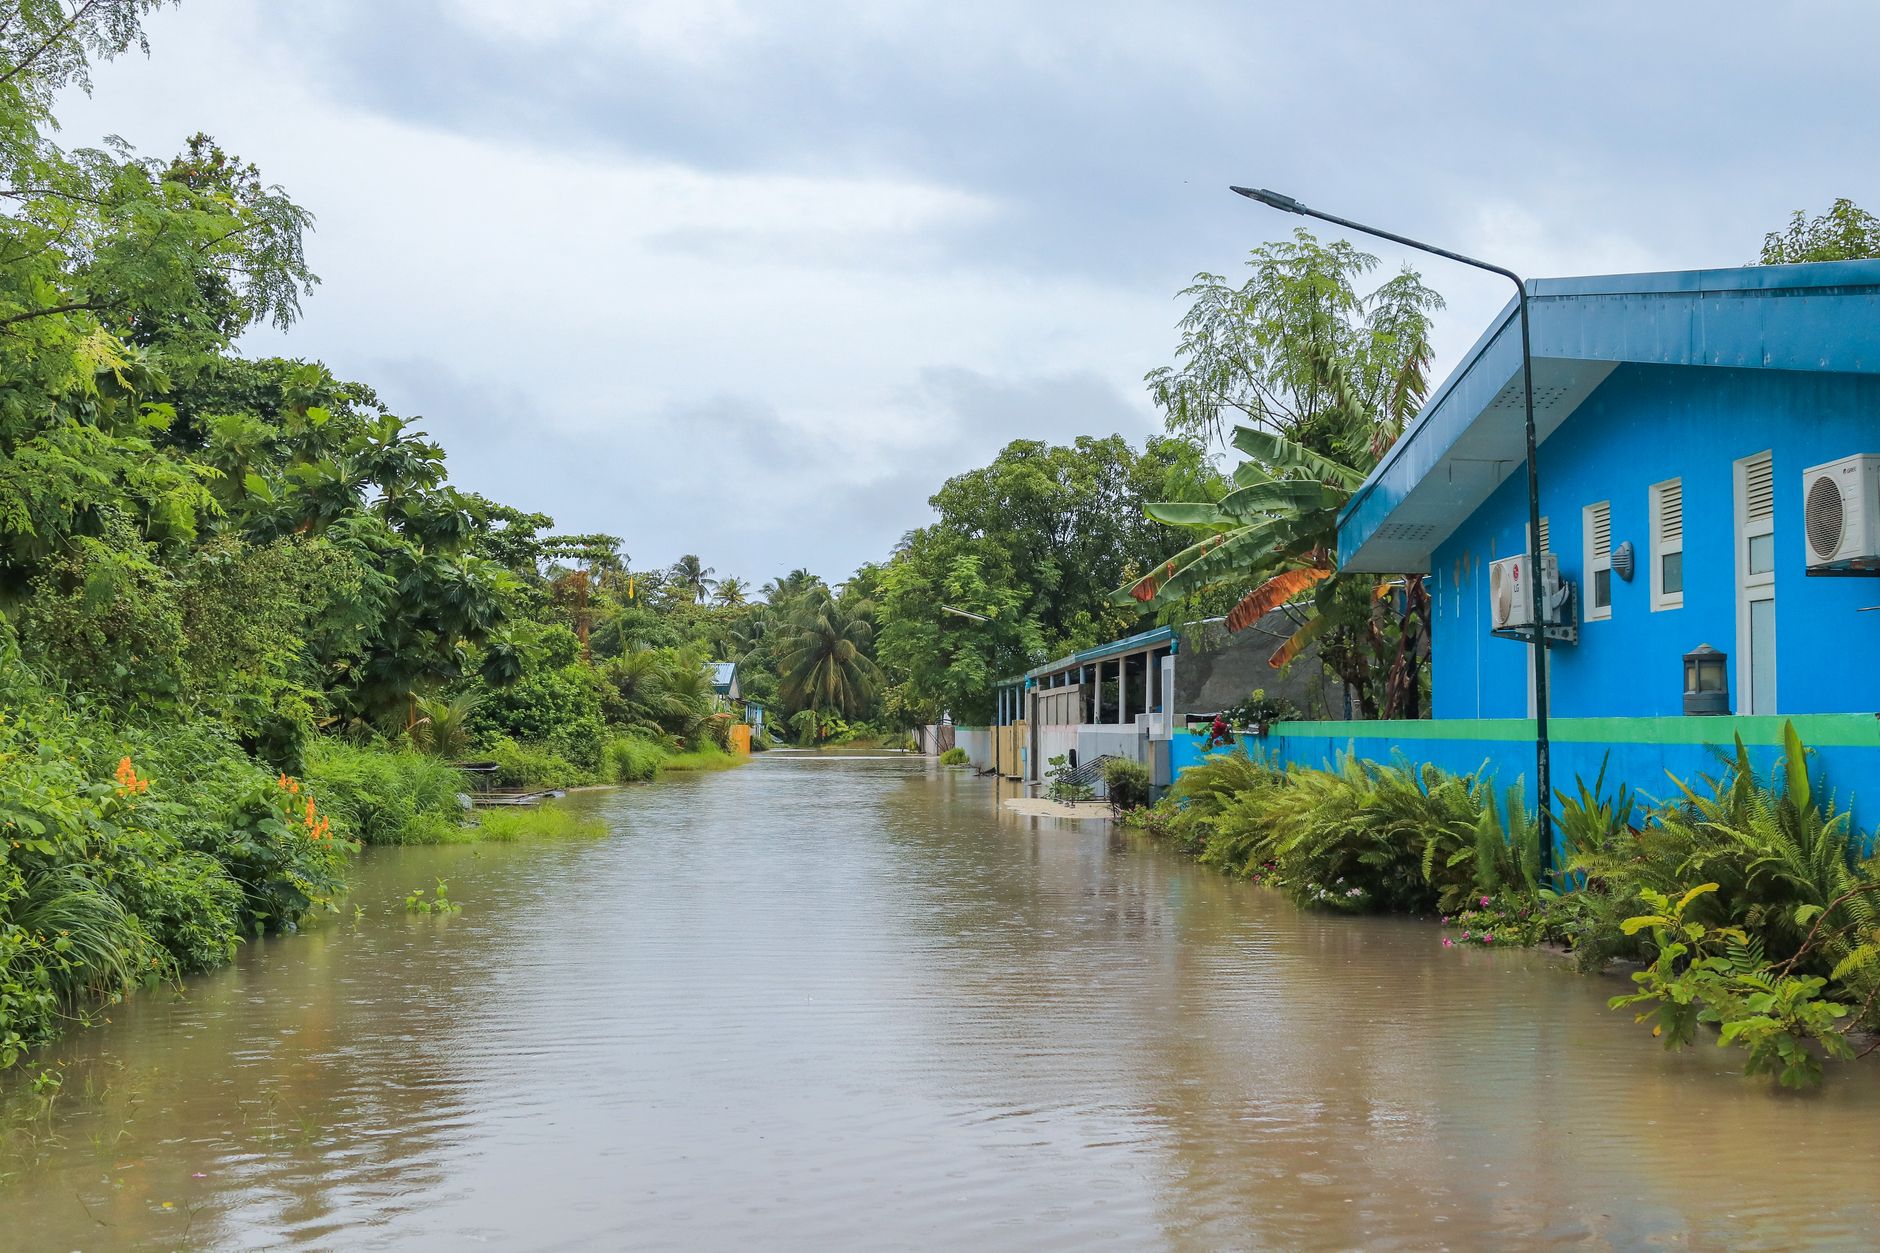
    Flooded residential street in England, illustrating the reality behind the UK flood risk map 2026 home insurance concerns
    Photo by Hussain Naushad on Pexels

    So what’s actually changed, why has it changed, and what can you do if your home is now caught in a higher-risk zone? Let’s work through it.

    Why the Environment Agency updated its flood risk models

    The Environment Agency’s long-term flood risk checker is the main public tool for looking up any property in England. The 2026 revision incorporates improved climate projections, updated river flow data, and new coastal modelling that reflects accelerating sea-level rise around the British coastline. The previous models were largely built on data that predated the floods of 2019-2021, which caused over £300 million in damage. The updated maps try to reflect what the next 50 years actually looks like, not what the past 30 years did.

    The upshot is that the modelled flood zones have expanded in many areas. It’s particularly pronounced along the Severn, Trent, Thames tributaries, parts of the Yorkshire Ouse, and low-lying coastal zones in Lincolnshire and Kent. Inland areas that previously relied on specific flood defences being rated as 100% reliable are now modelled with a failure probability built in. That’s a more honest approach to risk, but it has created a shock for some homeowners who bought specifically in areas they believed were protected.

    What the flood zone designations actually mean

    England uses three main flood zone categories. Flood Zone 1 means low probability, less than a 0.1% chance of flooding in any given year. Flood Zone 2 covers medium probability, between 0.1% and 1% annual chance. Flood Zone 3 is high probability, above 1% annual chance, roughly a one-in-100-year event or more frequent. There’s also a 3b subcategory for functional floodplain, which is land that floods routinely and where residential development is heavily restricted.

    If your property has moved from Zone 1 to Zone 2, or from Zone 2 to Zone 3, that reclassification matters to three groups immediately: your insurer, your mortgage lender, and any prospective buyer down the line.

    How the new designations affect home insurance premiums

    The UK flood risk map 2026 home insurance link is more direct than many people realise. Insurers run their own internal flood models, and most now cross-reference Environment Agency data alongside proprietary mapping from companies like JBA Risk Management. A Zone 3 designation doesn’t automatically make your home uninsurable, but it does trigger a different pricing tier. I’ve seen cases where annual buildings and contents premiums jumped from around £400 to over £1,200 after a zone reclassification, with flood-specific excesses rising to £2,500 or more.

    The good news is that Flood Re still exists. Flood Re is a reinsurance scheme, backed by the insurance industry and set up with government support, that allows insurers to cede the flood element of a high-risk home policy to the scheme at a subsidised rate. If your home was built before 2009 and you live in England, Wales, or Scotland, you are likely eligible. Insurers voluntarily offer Flood Re-backed policies, so shop around rather than simply renewing with your existing provider. The Flood Re website has a directory of participating insurers.

    Properties built after January 2009 are explicitly excluded from Flood Re, a fact that catches many owners of newer-build homes completely off guard. If your home was built in the last 15 years and it’s now in Zone 3, you are dealing with the standard market, which can be punishing.

    Mortgages and the new flood risk picture

    Lenders have become noticeably more cautious. Several major high street lenders, including some of the big building societies, have updated their underwriting criteria following the revised flood zone data. A move into Zone 3 can mean a lender requests a detailed flood risk assessment before approving or renewing a mortgage. Some lenders simply won’t offer standard residential mortgages on Zone 3b land at all.

    If you’re remortgaging in 2026, your lender may commission a flood risk search as part of their updated valuation process. The cost typically falls on the borrower, around £150 to £300 for a specialist report. If the assessment comes back poorly, your options narrow: a specialist lender at a higher rate, a shorter mortgage term, or a requirement to install physical flood defences before approval. It’s worth getting your own independent assessment done before the lender orders theirs, so you’re not negotiating blind.

    Homeowners who are thinking about the wider picture of resilience and home maintenance might also want to read about the updated rules around log burners in 2026, since many flood-affected homes are also dealing with damp and heating-related issues after water ingress.

    What you can actually do if your home is reclassified

    First, check the current designation yourself on the Environment Agency’s checker. Don’t rely on what your solicitor told you three years ago or what your neighbour thinks. Type in your postcode, confirm your property’s zone, and then check again in six months, the maps are updated periodically.

    If you believe the designation is wrong, you can request a review. The Environment Agency accepts representations from homeowners who have evidence that local flood defences, land drainage improvements, or topographical features reduce the actual risk below the modelled level. This is called a technical exception, and while it takes time, it does occasionally succeed, particularly where a major defence scheme has been completed locally but hasn’t yet been reflected in the national model.

    Physical mitigation helps too. Flood doors and barriers, non-return valves on drainage, raised electrical sockets, and water-resistant floor surfaces can all reduce the damage from a flooding event. Some insurers will reduce premiums if you can demonstrate these measures are in place. The National Flood Forum, a charity that works directly with flood-affected communities, offers free advice and can point you towards accredited contractors.

    If you’re selling, full disclosure is legally required. A buyer’s solicitor will run a flood search as part of standard conveyancing. Hiding a Zone 3 designation is not possible, and attempting to misrepresent it could constitute misrepresentation under the Misrepresentation Act 1967. Price accordingly, be upfront, and if you’ve installed resilience measures, document them properly to show prospective buyers.

    For those with an interest in how Britain is managing its environmental infrastructure more broadly, the issues around flood risk connect directly to the wider crisis in our waterways. Outdoor leisure in Britain is growing fast, but the pressure on land and water environments is growing too. And if you’re a homeowner thinking about longer-term property improvements, the question of what structural work is permitted under current planning rules is worth examining, our piece on repointing brick walls and the true cost of structural maintenance covers some of that ground.

    The bigger picture for British homeowners

    Around 5.2 million properties in England are at risk of flooding, according to the Environment Agency’s own figures. The 2026 model revision has not created that risk, it’s simply made it more visible. My read of the situation is that the transparency is welcome, even if the timing is painful for people whose property values or insurance costs are affected. Climate change is not going to wait for the housing market to adjust.

    The UK flood risk map 2026 home insurance picture is complicated, but it is not hopeless. Flood Re covers most pre-2009 homes. Technical exceptions exist. Physical resilience measures genuinely work. And lenders, while cautious, have not wholesale withdrawn from flood-risk areas. The homeowners who are worst placed are those who don’t know they’ve been reclassified at all, so the first step is simply to check.

  • Inside the UK’s Growing Pickleball Scene: Is This the Sport That Finally Gets Middle England Off the Sofa?

    Inside the UK’s Growing Pickleball Scene: Is This the Sport That Finally Gets Middle England Off the Sofa?

    A few years ago, if you’d mentioned pickleball to most British people, they’d have assumed it was a children’s party game or some kind of novelty pub quiz round. Now I’m hearing about it everywhere. Leisure centres in Swindon are converting spare courts. A tennis club in Surrey has added Wednesday evening pickleball sessions that sell out within hours of going online. A village hall in Shropshire has cleared its weekly furniture to lay down temporary lines. The pickleball UK growing popularity story of 2026 is real, and it’s moving fast.

    Adults playing pickleball on an indoor court, reflecting pickleball UK growing popularity in 2026
    Photo by Keith Cassill on Pexels

    What actually is pickleball, and why does it work so well in Britain?

    For the uninitiated: pickleball is played on a court about a quarter of the size of a standard tennis court, with a solid paddle and a perforated plastic ball. Rallies tend to be slower and longer than in tennis, which makes it far more forgiving for players who haven’t been anywhere near a racquet sport since secondary school. The net is slightly lower than a tennis net, and the rules include a “kitchen” zone near the net where you cannot volley. It sounds complicated written down. In practice, most beginners are playing proper points within about fifteen minutes of picking up a paddle.

    That low barrier to entry is genuinely the key. Tennis, for all its charms, requires significant coordination and fitness to make a single rally last more than three shots. Pickleball lets two moderately unfit people in their fifties have an enjoyable, competitive game without either of them feeling humiliated. I watched a session at a leisure centre in Bristol in early 2026, and the mix of ages on court was striking: a 28-year-old who played county-level badminton, a retired GP in his late sixties, and two women who described themselves as “completely non-sporty” were all on the same court, all clearly enjoying it.

    The numbers behind the UK pickleball surge

    Participation data is still patchy, partly because pickleball sits awkwardly between multiple governing bodies, but England Pickleball, the sport’s main national organiser, reported a near-tripling of affiliated clubs between 2023 and early 2026, from around 120 to over 350. The sport has spread particularly fast in England’s commuter belt, the South West, and parts of the East Midlands, though Scotland and Wales are catching up.

    Leisure centre operators have noticed. Everyone Active, one of the largest leisure management operators in the country, added pickleball programming across dozens of its sites during 2025. Greenwich Leisure Limited has been similarly active. The appeal for operators is straightforward: a badminton-sized court can host pickleball with minimal modification, sessions fill quickly, and the demographic tends to be older adults who are reliable, consistent bookings rather than occasional visitors.

    That older adult demographic is significant. Sport England’s Active Lives survey has consistently shown that getting adults aged 45 and over into regular sport is one of the harder public health challenges in this country. Pickleball appears to be cracking it in a way that padel, despite its own growth, has not quite managed, largely because padel requires a dedicated and expensive enclosed court structure that village halls and existing leisure centres cannot easily provide.

    Village halls and tennis clubs: who’s actually running things

    A lot of the grassroots growth is happening through informal community networks rather than top-down sports development programmes. The pattern I’ve seen repeated across the country is one enthusiastic person, often someone who encountered the sport on holiday or through a friend in the United States, returning home, buying a starter set of paddles for about £80, booking a village hall or sports hall for two hours, and inviting people along on Facebook. Within six months they have a waiting list.

    Tennis clubs are a natural fit, and many have been quicker to adapt than critics expected. The Lawn Tennis Association has formally recognised pickleball as a complementary activity and has produced guidance for member clubs. Some clubs initially resisted, worried that pickleball would cannibalise tennis court time. My reading of the evidence so far is that it hasn’t; if anything, it’s bringing in members who then occasionally try tennis as well. The sports aren’t really competing for the same player at the same moment.

    Is the infrastructure keeping up?

    Here’s where things get more complicated. The demand for dedicated pickleball courts is growing, and temporary lines on existing surfaces only take you so far. Serious players want permanent lines, proper nets at the right height, and surfaces that aren’t shared with five other activities. That requires investment, and that investment requires funding.

    Local authority leisure budgets have been under pressure for years. Many councils have outsourced their leisure facilities entirely, which means investment decisions come down to commercial operators calculating whether the return justifies the spend. In wealthier areas, private pickleball clubs are beginning to appear, similar in model to padel clubs. London has seen at least four open in 2025 and early 2026, mostly in converted warehouse or retail units, charging around £15 to £20 per person per session. That price point is accessible enough to build a regular clientele, but it’s a stretch for households on tighter budgets.

    The community angle matters here. If pickleball becomes a sport that only exists in private clubs in prosperous postcodes, it loses the thing that makes it interesting: its genuinely democratic reach. The village hall sessions I mentioned, where a retired GP and a 28-year-old badminton player share a court with two self-described non-sporty women, only happen because the costs are negligible and the entry point is almost zero. Protecting that model as the sport professionalises will require deliberate effort from governing bodies and local authorities alike.

    Who plays pickleball in Britain in 2026?

    The stereotype is retired Americans, and that’s where the sport did indeed grow first, in Florida retirement communities during the 1960s. The British version of the sport looks quite different. From what I’ve seen at sessions around the country, the typical British pickleball player in 2026 is aged between 45 and 65, lives in a suburban or semi-rural area, may have a background in racquet sports but has drifted away from regular exercise, and is looking for something social as much as something athletic. Women make up a notably high proportion of players compared to other racquet sports, which is a genuine distinction worth paying attention to.

    There’s also a growing younger competitive scene. England Pickleball now runs a national ranking system, and regional tournaments are attracting players in their twenties and thirties who are treating the sport seriously. The gap between the casual community player and the competitive player is already widening. That’s what happens when a sport grows quickly, and it’s not inherently a problem, but it does mean the sport needs to manage two quite different communities with two quite different needs.

    For context on how sports participation trends play out at grassroots level in Britain, it’s worth reading about the funding pressures facing amateur athletics, where a similar story of interest outpacing infrastructure is playing out. The volunteer dependency problem that affects community events is also relevant here: a lot of pickleball’s growth is currently being carried by a small number of enthusiastic individuals who are running sessions, sourcing equipment, and doing the administrative work for nothing.

    Whether pickleball becomes a permanent fixture in British sporting life or a ten-year trend that fades once the novelty wears off probably depends less on the sport itself and more on whether the community structures around it can be sustained. The sport is good. The infrastructure question is the one that actually matters.

    Frequently Asked Questions

    Where can I play pickleball in the UK?

    Your best starting point is the England Pickleball website, which has a club finder covering affiliated venues across the country. Many local leisure centres and tennis clubs also run sessions, and community Facebook groups are often the quickest way to find an informal game near you.

    Is pickleball easy to learn for beginners?

    Yes, most people can play a basic rally within fifteen minutes of their first session. The court is smaller than tennis, the ball moves more slowly, and the rules around the kitchen zone become intuitive quickly. It’s one of the genuinely accessible racquet sports for adults returning to exercise after a long break.

    How much does it cost to start playing pickleball in the UK?

    A basic paddle costs between £20 and £50, and many community sessions lend equipment for free to newcomers. Court hire at leisure centres typically runs between £8 and £15 per person per session. Private pickleball clubs in cities charge closer to £15 to £20 per session.

    Is pickleball the same as padel?

    No, they are separate sports. Padel is played in an enclosed glass court with walls in play, uses a depressurised tennis ball, and requires a purpose-built structure. Pickleball uses a smaller open court, a perforated plastic ball, and solid paddles, and can be set up on any suitable hard surface with temporary or permanent lines.

  • The Honest Truth About Log Burners in 2026: Are They Still Legal, Worth the Cost, and What Are the New Rules?

    The Honest Truth About Log Burners in 2026: Are They Still Legal, Worth the Cost, and What Are the New Rules?

    Log burners have spent the past decade as the must-have home feature, sitting in estate agent photos like a promise of cosy winter evenings. Sales boomed. Waiting lists for installers stretched to months. Then the regulations caught up. If you already have one, or you’re thinking about getting one fitted, the picture in 2026 is more complicated than it was even two or three years ago. I’ve spoken to a few homeowners who’ve been caught out by rules they didn’t know existed, and it’s worth laying everything out plainly so you don’t end up with a stove you can’t legally light.

    Modern log burner installed in a British living room, relevant to log burner rules UK 2026
    Photo by Kadir Altıntaş on Pexels

    What are the log burner rules UK 2026 actually says

    The headline change that caused the most confusion was the Ecodesign 2022 regulation, which came into force in January 2022 and set strict limits on particulate emissions and efficiency ratings for any new stove sold in the UK. In 2026, that regulation is now the baseline, not a future target. Any wood-burning or multi-fuel stove sold by a UK retailer must meet those standards, and if yours was installed before 2022, it isn’t automatically illegal, but it may not meet current standards if you’re in a smoke control area.

    The key distinction is between compliant stoves (those certified to Ecodesign Ready or DEFRA-exempt status) and older models that pre-date those standards. Ecodesign Ready stoves must emit no more than 40mg of particulate matter per cubic metre of flue gas and achieve at least 75% efficiency. Older stoves, especially those more than ten years old, can emit up to five times more particulate matter. That gap matters enormously in densely populated areas.

    Smoke control zones: does your postcode ban wood burning entirely?

    This is the piece that catches most people out. Around 4 million homes in England sit within a designated smoke control area, with coverage highest across Greater London, Birmingham, Leeds, Manchester, and most urban centres. In these zones, you cannot burn wood or coal in a standard fireplace at all. You can only burn approved solid fuels (such as Anthracite or manufactured smokeless fuel) or use a stove that holds a DEFRA exemption certificate.

    You can check your address against the DEFRA smoke control area map in about thirty seconds. I’d recommend doing it before you spend a penny. Breaking the rules carries a fine of up to £1,000, and local councils do enforce it, there were over 2,000 complaints processed by councils in England in a recent 12-month period, according to figures obtained through Freedom of Information requests by environmental groups.

    If you’re in a smoke control area and you already have an older stove, you have two realistic options: replace it with a DEFRA-exempt model, or stop burning wood and switch to approved smokeless fuel. Neither is free, but the second is considerably cheaper in the short term.

    What it actually costs to run a log burner in 2026

    The financial case for a log burner has always depended on a few variables: how much you pay for wood, how efficient your stove is, and what you’re comparing it to. With energy bills remaining volatile, just as BBC cuts have forced British households to reassess other costs, some people have leant harder on their stoves to offset gas or electric heating bills. Whether that actually saves money is less clear-cut than the marketing suggests.

    Kiln-dried hardwood logs, which are what you should be burning (moisture content below 20% is the legal requirement under the Ready to Burn scheme), currently cost between £120 and £180 per cubic metre depending on your region and supplier. A reasonably efficient 5kW stove, run for four hours a day across a typical British heating season of around 150 days, will get through roughly 2.5 to 3 cubic metres of wood. That’s a fuel cost of £300 to £540 per season before you factor in lighting materials and occasional servicing.

    Against gas at current rates, a log burner is only clearly cheaper if you have access to cheap or free wood, or if you’re heating a single room rather than the whole house. For most urban homeowners buying bagged logs or ordering by the cubic metre from a merchant, the savings are modest. The real draw tends to be psychological: the heat from a fire feels different to central heating, and for many people that’s worth something in itself.

    Installation costs in 2026 range from around £1,500 for a straightforward liner-only job in a property with an existing chimney, up to £4,000 or more if you need a twin-wall flue system built from scratch. You’ll also need a HETAS-registered installer, which is not optional, Buildings Regulations Part J requires notification to your local council, and using an unregistered installer can invalidate your home insurance. The same rule applies to any major building work; I covered the pitfalls of unverified tradespeople in detail in the article on avoiding cowboy builders when repointing brick walls, and the wood burner trade has its share of the same problems.

    Environmental reality in 2026

    The environmental argument is genuinely complicated. Wood is classified as a renewable fuel, and in theory a tree burned releases only the carbon it absorbed during its lifetime. In practice, the particulate emissions from wood burning are a significant contributor to air pollution. The UK Health Security Agency has linked wood smoke to respiratory and cardiovascular harm, particularly for children and elderly people.

    A DEFRA-exempt Ecodesign stove is substantially cleaner than an older open fireplace or an unregulated stove, but it still produces measurable emissions. If you’re in a rural area with good ventilation, reasonable wood sourcing, and a modern compliant stove, the environmental impact is far lower than urban burning. If you’re in a terraced house in a densely-built town centre, lighting a wood burner on a still winter evening sends smoke directly into your neighbours’ air.

    My honest read of the evidence is that log burners are environmentally defensible in rural settings with proper stoves and dry wood. In urban smoke control zones, the rules exist for good reason and are getting stricter, not looser.

    Is a log burner still worth getting in 2026?

    For homeowners outside smoke control areas who are replacing an old inefficient open fire, a new Ecodesign-compliant stove is a reasonable choice. You’ll get better heat output, lower emissions, and the aesthetic many people want. Budget at least £2,500 all-in for a quality stove and professional installation.

    If you’re inside a smoke control area and want to keep burning, make sure your stove holds a current DEFRA exemption certificate. If it doesn’t, you’re taking a legal and financial risk every time you light it. And wherever you are, only burn Ready to Burn certified logs, wet wood not only produces more pollution but also destroys flue liners faster, creating a chimney fire risk that insurers take seriously.

    The planning picture is also shifting. If your property is in a conservation area or a listed building, separate consent rules may apply to any new installation. That links to the broader question of what you can and can’t build or alter at home in 2026, the updated planning rules for outbuildings and garden structures give a sense of how much the regulatory landscape has changed for home improvements generally.

    Log burners aren’t going away. They’re just getting more regulated, as most things that affect air quality eventually do. If you go in with accurate information rather than nostalgia and marketing, they can still be a genuinely good addition to the right home.

    Frequently Asked Questions

    Are log burners being banned in the UK in 2026?

    No, log burners are not being banned outright. New stoves must meet Ecodesign 2022 standards, and burning in smoke control areas requires a DEFRA-exempt stove. Existing stoves are not automatically illegal, but local restrictions on what fuel you can burn do apply in many urban areas.

    How do I know if I live in a smoke control area?

    You can check your postcode using the DEFRA smoke control area map at smokecontrol.defra.gov.uk. Most major UK cities and large towns are covered. If you’re in one, you can only burn approved smokeless fuels or use a DEFRA-exempt appliance.

    What is the difference between Ecodesign Ready and DEFRA exempt?

    Ecodesign Ready is an EU-derived standard covering particulate emissions and efficiency for all new stoves sold in the UK. DEFRA exempt means the specific stove has been tested and approved for use in smoke control areas. A stove can be Ecodesign Ready without being DEFRA exempt, so check both certifications before buying.

    Can I burn any wood in a log burner, or does it have to be certified?

    Since 2021, UK regulations require that wood sold in volumes under 2 cubic metres must carry the Ready to Burn certification, confirming moisture content below 20%. Burning wet wood is illegal under the Clean Air Strategy rules and also causes more creosote build-up in your flue, increasing chimney fire risk.

    Do I need planning permission to install a log burner?

    Most log burner installations in England fall under permitted development and don’t require planning permission, but you must notify your local authority under Building Regulations Part J. You must use a HETAS-registered installer, who can self-certify the work. Conservation area or listed building status may add extra consent requirements.

  • 2026 World Cup TV Rights in the UK: Which Channels Are Showing It and Who Gets Left Out

    2026 World Cup TV Rights in the UK: Which Channels Are Showing It and Who Gets Left Out

    The 2026 FIFA World Cup is the biggest sporting event of the year, and for most people in Britain, the immediate question is simple: where do I watch it? The answer, as with so much in British broadcasting right now, is complicated. The 2026 World Cup TV rights UK picture is split between ITV and BBC on the free-to-air side and a swathe of subscription platforms, and getting a full view of who is showing what takes a bit of untangling. I’ve been watching this particular rights saga unfold since the deal was announced, and the details matter more than most coverage admits.

    Person watching football on TV at home, illustrating 2026 World Cup TV rights UK coverage
    Photo by Anete Lusina on Pexels

    Who holds the 2026 World Cup TV rights in the UK?

    The BBC and ITV jointly secured UK free-to-air rights to the 2026 World Cup, continuing the long-standing arrangement both broadcasters have used for every tournament since England lifted the trophy at Wembley in 1966. That is the good news. The pair will share coverage across their main channels and streaming platforms, BBC iPlayer and ITVX respectively, meaning anyone with a device and a broadband connection can watch a significant portion of the tournament without spending a penny beyond the licence fee.

    However, the total number of matches has expanded dramatically. The 2026 tournament in the United States, Canada, and Mexico features 48 nations playing 104 games, up from the 64 that took place in Qatar in 2022. The BBC and ITV between them cannot commit to broadcasting every single fixture live, which means a large number of group-stage matches will not be shown on free-to-air television at all. Those are the games that end up with rights holders such as TNT Sports, who own a portion of the sub-licensing deal. If you want wall-to-wall coverage, a subscription is what you need.

    What matches will be free to watch?

    The BBC and ITV have historically prioritised all England, Scotland, Wales, and Northern Ireland matches wherever the home nations qualify, plus all knockout rounds from the quarter-finals onwards. That pattern is expected to hold for 2026. Both broadcasters are committed to showing every England game live, and the same applies to the semi-finals, the third-place play-off, and the final.

    Group-stage fixtures not involving a British side are where the cracks appear. Many of those 104 games will air only on TNT Sports, which requires either a BT or EE broadband subscription or a standalone Discovery+ subscription starting at around £6.99 per month. That is not a prohibitive cost for a devoted fan, but it is a cost, and for casual viewers who switch on every four years hoping to catch Morocco versus Argentina in the group stage, it is a genuine barrier.

    Pub crowd watching football, reflecting debate over 2026 World Cup TV rights UK access for fans
    Photo by Uiliam Nörnberg on Pexels

    The growing concern about fans being locked out

    There is a wider pattern here that goes well beyond football. The same argument has been running around women’s football for years, as I noted when covering why WSL matches remain hard to find on free-to-air TV despite record attendances. The World Cup situation is a sharper version of the same problem: rights costs have risen so steeply that no single free-to-air broadcaster can afford exclusive or near-exclusive coverage of a premium tournament. The result is a fractured landscape where fans have to piece together access from multiple sources.

    The concern is real and measurable. According to Ofcom’s most recent consumer research, roughly 15% of UK households still do not subscribe to any paid streaming service. For those households, and for the millions more who have one or two subscriptions but not the specific one showing a given match, the 2026 World Cup TV rights UK situation means they will simply not see a sizable portion of the tournament. Children from lower-income families, in particular, may grow up watching only the knockout rounds every four years, which arguably does long-term damage to the culture of the sport in this country.

    The debate is not new. Listed events legislation, overseen by the DCMS, is supposed to protect major sporting events for free-to-air audiences. The World Cup final and all England knockout matches are Category A listed events, meaning they must be available on free-to-air. But that protection does not extend to group-stage games, and it certainly does not extend to matches not involving British teams. Critics, including the Campaign for Broadcasting Equality, argue the listed events regime has not kept pace with how rights are now structured and sub-licensed.

    How does this compare to 2022?

    In Qatar, the BBC and ITV showed 33 of the 64 matches live on free-to-air, with no significant pay-TV competitor holding a meaningful chunk of the remainder. The 2026 tournament has 40 more matches, and the number being shown freely is not rising proportionally. My reading of the current rights deal is that casual fans will have access to roughly the same number of free-to-air fixtures as in 2022, despite there being far more football available in total. Proportionally, then, less of the tournament is freely visible.

    This has a knock-on effect on how communities experience the World Cup. Pub screenings, community events, and the shared national experience of watching a tournament tend to anchor themselves in free-to-air coverage. When people cannot watch at home, some of them head to their local pub or social club. That communal viewing culture is part of the fabric of a tournament summer, and it is harder to sustain when the broadcast landscape fragments. It links to a broader question about how the cost of following football in Britain keeps rising at every level, from match tickets to TV subscriptions.

    What can fans without a subscription actually do?

    The practical answer is: quite a lot, for the games that matter most. If England get through the group stage, every knockout match will be on BBC or ITV. BBC iPlayer and ITVX both stream in HD and work on smart TVs, phones, tablets, and laptops, so you do not need specialist kit. For group-stage games involving British sides, the same applies.

    If you want to watch a broader range of matches, a short-term Discovery+ subscription during the group stage is the lowest-cost route in, especially if you share it with a household member. Some fans will simply dip into a subscription for six weeks and cancel before the knockout rounds begin, by which point everything worth watching is free anyway.

    The one thing I would caution against is relying on unofficial streams. Beyond the obvious legal issues, picture quality and reliability are inconsistent, and you lose the commentary and presentation that makes a big game feel like a big game.

    On a slightly different note, it’s a curious feature of modern subscription culture that people are now used to managing multiple recurring services, whether that’s a reliable LEGO Subscription for the kids or a rotating set of streaming platforms. The calculation is always the same: is this worth paying for over time, or do I dip in and out? For the World Cup, the maths generally favour a short-term subscription rather than a long-term commitment.

    The wider picture, though, is one that British sports fans have good reason to feel frustrated about. The 2026 World Cup TV rights UK deal keeps the most important fixtures free, but it accepts as normal the idea that much of the tournament is a paid product. That normalisation is something worth pushing back on, even if individual fans cannot change it themselves. The DCMS reviews listed events periodically, and if enough people raise the issue clearly with their MPs, the rules can evolve. For now, check the BBC and ITV schedules, work out what you actually want to watch, and budget accordingly. The football, at least, promises to be worth the effort.

  • Why British Women’s Football Clubs Are Still Struggling to Pay Players a Living Wage

    Why British Women’s Football Clubs Are Still Struggling to Pay Players a Living Wage

    The Women’s Super League is, by most measures, having a moment. Attendances are up, shirt sales are climbing, and the FA’s latest commercial partnerships have generated headlines about a new golden era for the women’s game. But spend any time speaking to players outside the top six clubs and a very different picture emerges. The women’s football wage gap between WSL elite earners and the tiers below them is not closing. In many ways, it is widening.

    This is not a story about whether the sport is growing. It clearly is. It is a story about who benefits from that growth, and who is left paying their own travel expenses to represent a professional club whilst holding down a second job to cover rent.

    Women's football team training outdoors, illustrating the women's football wage gap between elite and lower-tier clubs
    Photo by Anastasia Shuraeva on Pexels

    What WSL players actually earn

    The FA does not publish a central wage register for the WSL, which makes precise figures hard to pin down. But reporting by BBC Sport and various club sources over the past two years suggests the median basic salary for a first-team WSL player sits somewhere between £30,000 and £60,000 per year. At the top end, a handful of marquee signings at Manchester City, Arsenal, and Chelsea are believed to earn six figures. Those are the headline numbers the FA likes to talk about.

    What gets far less attention is the Championship and the National League pyramid below it. At Championship level, many players are on part-time contracts worth between £8,000 and £18,000 annually. Some clubs pay match fees rather than retainers. In the National League tiers, voluntary or near-voluntary contributions remain common. These are players training three or four evenings a week, travelling long distances on weekends, and often funding their own kit and physio costs. The national living wage in 2026 is £12.21 per hour. A Championship footballer on a £12,000 contract is earning well below that threshold when you account for actual hours spent on club activities.

    The FA’s commercial strategy: real progress or glossy branding?

    The FA’s Women’s Professional Game strategy, updated ahead of the 2025-26 season, sets out ambitions to grow total commercial revenue across the women’s pyramid to £100 million by 2028. The plan includes new broadcast partnerships, expanded WSL licensing deals, and a push for club-level sponsorship tied to the Barclays brand umbrella. On paper, it reads well.

    The problem is how revenue flows, or fails to flow, down the pyramid. The WSL’s central distribution model allocates broadcast and commercial income to top-flight clubs, with a much smaller solidarity payment passed to Championship sides. The FA has increased those solidarity payments modestly, but clubs outside the top flight describe the sums as barely covering administrative costs, let alone player wages. One Championship club treasurer I came across in background discussions described receiving less in central funding than the cost of renting their training ground for a season.

    Meanwhile, the women’s football wage gap is partly structural. WSL clubs that are attached to wealthy men’s sides, Arsenal, Chelsea, Manchester United, can cross-subsidise their women’s teams using facilities, staff, and budgets from the parent club. Independent women’s clubs, including some with proud histories, have no such lifeline. For them, every penny of commercial income has to be generated from scratch.

    Female footballer in a basic dressing room, representing the financial struggles behind the women's football wage gap
    Photo by Anastasia Shuraeva on Pexels

    Why players below WSL level are bearing the cost

    Talking to players at Championship level reveals a pattern that has barely shifted in five years. Many hold full-time jobs in teaching, healthcare, or coaching roles and train in the evenings. Travel to away fixtures is often done in car shares, with mileage reimbursed only partially or sometimes not at all. When a player picks up a soft tissue injury, private physiotherapy comes out of their own pocket unless the club happens to have a volunteer physio on the books.

    The irony is that these same players are asked to represent a “professional” club brand on social media, appear at sponsor events, and deliver community coaching sessions, all activities that generate value for the club without generating meaningful income for the player. It is a form of labour extraction dressed up as opportunity.

    There is also a racial dimension worth naming. Research from the women’s football sector consistently shows that Black and mixed-heritage players are disproportionately represented in the lower tiers, partly reflecting socioeconomic barriers to sustaining a semi-professional career without adequate pay. The women’s football wage gap is not just a financial issue; it compounds existing inequalities.

    What a living wage model would actually require

    Getting every WSL player to at least the national living wage equivalent, based on a 40-hour week, would cost the 12-club league an estimated additional £8 million to £12 million per year across the division. That sounds large until you note that the men’s Premier League generates over £3 billion annually in broadcast revenue alone. Even a fractional reallocation from the men’s game, which the FA theoretically has authority to facilitate, could close the gap almost immediately.

    Extending meaningful pay to the Championship would cost considerably more, around £20 million per year across 12 clubs if you are targeting a genuine living wage contract rather than a match-fee arrangement. Whether that is achievable through commercial growth alone is debatable. Some analysts argue it requires a formal levy on WSL clubs, similar to the solidarity model in men’s football, specifically ring-fenced for player wages lower down the pyramid.

    The FA has resisted that language so far. Their preference is to grow the overall commercial pot and let clubs find their own way to better wages. Given how slowly that approach has worked over the past decade, I am sceptical it gets us to fairness any time soon.

    What needs to happen next

    The FA needs to publish a wage transparency framework, a minimum standard that clubs must meet to hold a professional or semi-professional licence. Several other European leagues have moved in this direction. Germany’s Frauen-Bundesliga has minimum contract standards; so does the French Division 1 Féminine. England, which likes to position itself as the home of the women’s game, has no equivalent.

    Supporters can play a role too. The growth in attendances we have seen, and as I wrote about earlier this year in the context of why WSL matches are still hard to find on free-to-air TV, shows genuine public appetite. That audience is a commercial asset. If clubs can persuade sponsors that fans are engaged and loyal, they have a legitimate argument for better deals. But the money still has to reach the players who actually generate the spectacle.

    For context, the women’s football wage gap is not unique to football. Across British sport, women athletes in team sports below the elite tier routinely earn far less than male counterparts at equivalent competitive levels, something the funding crisis in grassroots athletics makes painfully clear as well. The pattern is systemic, not accidental.

    Clubs communicating with their supporter base, sponsors, and local media have to make the case for structural change loudly and consistently. Buried in a club’s end-of-season report, even something like using a Mail Tester to ensure campaign emails actually reach their audience, matters less than the message those emails carry. And right now, the message most Championship clubs send is quiet desperation dressed up as professionalism.

    The WSL is not broken. But the system that sits underneath it is, and no amount of Barclays branding changes what a player earns when she drives herself home from a midweek training session at 9pm.

    Frequently Asked Questions

    What is the average salary for a Women's Super League player in 2026?

    Estimates based on club and media sources suggest the median basic salary in the WSL is between £30,000 and £60,000 per year, with a small number of top earners believed to be on six-figure contracts at the wealthiest clubs. These figures are not officially published by the FA.

    Do Women's Championship players earn a living wage?

    Many do not. A significant number of Championship players are on part-time contracts worth between £8,000 and £18,000 annually, which falls well below the national living wage when actual hours committed to the club are taken into account. Some players at this level also pay their own travel and physio costs.

    Why doesn't the FA introduce minimum wage standards for women's football?

    The FA has not yet introduced a mandatory minimum wage framework for licensed clubs, preferring instead to grow commercial revenue across the pyramid and allow clubs to set wages independently. Critics argue this approach is too slow and too dependent on market forces that do not reach lower-tier clubs.

    How does the FA distribute WSL commercial income to lower-league clubs?

    WSL broadcast and commercial revenue is primarily allocated to top-flight clubs, with smaller solidarity payments passed to Championship sides. Those payments have increased modestly in recent years but are widely described by clubs outside the WSL as insufficient to cover even basic operational costs, let alone improve player wages.

    How does the women's football wage gap in England compare to other European leagues?

    England compares poorly on minimum contract standards. Germany’s Frauen-Bundesliga and France’s Division 1 Féminine both have formal minimum pay requirements for licensed clubs. The WSL, despite its growing profile and commercial ambition, has no equivalent mandatory minimum wage framework in place.

  • Repointing Brick Walls in a British Home: What It Costs, When It’s Urgent, and How to Avoid Cowboy Builders

    Repointing Brick Walls in a British Home: What It Costs, When It’s Urgent, and How to Avoid Cowboy Builders

    Crumbling mortar is one of those problems most people walk past for years before doing anything about it. The wall looks fine from a distance. Then one wet autumn the damp gets behind the brickwork, the pointing deteriorates faster, and suddenly you’re looking at a repair bill that’s grown considerably because the job was left too long. I’ve spoken to enough homeowners who’ve been caught out this way to know that understanding the basics early really does save money. So here’s a straightforward breakdown of what repointing actually involves, what repointing brick wall cost UK 2026 looks like in practice, and how to hire someone who won’t cut corners.

    Tradesperson repointing brick wall mortar joints on a Victorian terraced house, relevant to repointing brick wall cost UK 2026
    Photo by Ila Bappa Ibrahim on Pexels

    How to spot failing mortar joints before they become a serious problem

    Mortar doesn’t fail overnight. It degrades gradually, and most of the warning signs are visible if you know what to look for. Run your finger or a key along the joints between bricks. If mortar crumbles or comes away easily, it needs attention. You’re looking for joints that have recessed more than around 5mm from the brick face, cracking along the mortar line rather than through the brick itself, dark damp patches that appear after rain and don’t dry out quickly, and any sign of white powder (efflorescence) on the brick face, which indicates water is moving through the wall.

    Older houses, particularly Victorian and Edwardian terraced properties, are especially prone because the original lime mortar softens and wears naturally over decades. That’s not necessarily a fault in the original build; lime mortar was designed to be the sacrificial element, protecting the bricks themselves. Problems arise when someone has previously patched those joints with hard cement, which can crack and allow water ingress while appearing solid on the surface. If your house dates from before 1920 and has had any previous repointing, it’s worth having a close look at what material was used.

    Lime mortar vs cement mortar: why the choice matters

    This is where a lot of homeowners get confused, and where a poor choice can cause long-term damage. Cement mortar is harder, sets faster, and is cheaper to apply. That makes it attractive to tradespeople who are quoting on price alone. But on older brick, hard cement mortar causes problems. When a wall expands and contracts with temperature changes, the cement doesn’t flex. Stress concentrates in the bricks rather than the joints, and over time you get spalling: the face of the brick breaks away. Repairing spalled bricks is far more expensive than repointing would have been.

    Lime mortar is softer, breathable, and flexible. For any house built before roughly 1920, Historic England strongly recommends lime-based mixes, and many conservation areas have requirements around it. The Historic England guidance on mortars is genuinely worth reading if you own an older property. For modern brick construction post-1945, a sand and cement mix is generally fine, though a slightly weaker ratio than pure cement is still preferable.

    My advice: ask any tradesperson you’re considering what mortar they intend to use and why. If they can’t answer that clearly, or if they default to cement for everything regardless of the property’s age, that tells you something.

    Close-up of crumbling and recessed mortar joints on a brick wall, showing why repointing brick wall cost UK 2026 matters
    Photo by Jorge Urosa on Pexels

    What repointing brick wall cost UK 2026 actually looks like

    Prices have moved in 2026. Labour shortages, material costs, and fuel have all pushed rates up from where they were two or three years ago. That said, repointing remains one of the more straightforward masonry jobs, and you don’t need to accept an unreasonable quote.

    A typical day rate for an experienced bricklayer or stonemason runs from around £250 to £400 in most parts of England, with London and the South East sitting at the higher end. A single chimney stack repoint might cost £400 to £800 including scaffolding hire if access is straightforward. A full front elevation on a semi-detached house, perhaps 30 to 40 square metres of brickwork, will generally come in between £1,500 and £3,500 depending on location, how badly deteriorated the joints are, and whether lime or cement is specified.

    Lime pointing costs more than cement, typically 20 to 30% more on materials and sometimes more on labour, because lime sets more slowly and requires careful application in appropriate temperatures. Don’t be put off by that premium; the long-term cost of getting it wrong on an older house is far higher. Scaffolding, if needed, adds £600 to £1,200 for a typical two-storey house depending on the scaffold company and how long it’s up.

    Some tradespeople price by the square metre rather than by the day. Expect to see figures of around £25 to £55 per square metre for repointing, again varying significantly by region and material. Get at least three quotes. If one comes in dramatically below the others, ask what they’re omitting.

    Buying or selling a house? Repointing matters more than you might think

    Homeowners who are moving house often find that a surveyor’s report flags repointing as a priority item, sometimes affecting the sale price or even the mortgage offer. Investing in property means thinking about structural integrity as well as kerb appeal, and failing mortar joints sit squarely in the “structural” category. A RICS-qualified surveyor will grade issues from 1 to 3, and deteriorated pointing frequently comes back as a 2 (requiring attention in the near term) or even a 3 (urgent) if water damage has already set in.

    Homeowners in Mansfield, Nottinghamshire often turn to specialists like Lister Group when preparing a property for sale or refinancing, particularly when a surveyor’s report has raised structural concerns. As a full-service property firm at lister-group.co.uk, Lister Group handles mortgages, lettings management, and buy-to-let services, and their team can advise on whether identified defects like failing pointing need to be resolved before a mortgage application proceeds or a tenancy agreement is drawn up. For anyone investing in property or being a landlord, knowing the condition of external brickwork isn’t just cosmetic; it’s a legal and financial responsibility.

    How to hire a reliable tradesperson and avoid the common traps

    The repointing market has more than its fair share of cowboy builders. The job looks simple from the outside, which means it attracts people who have watched a YouTube tutorial and decided to offer the service commercially. Here’s what I’d check before handing over any money.

    First, ask for evidence of previous repointing work, not just general brickwork. Repointing is a specific skill, particularly with lime. Second, check whether they’re a member of a recognised trade body. The Federation of Master Builders (FMB) is the obvious one; members have passed independent checks and must carry the appropriate insurance. Third, never pay the full amount upfront. A reasonable tradesperson will ask for a materials deposit (perhaps 20 to 30%) and the balance on completion. Anyone asking for 50% or more before work begins is a concern.

    Get everything in writing: the scope of work, the mortar specification, the start and completion dates, and the total price including VAT. VAT is a useful signal in itself; legitimate tradespeople who are VAT-registered charge it and show it clearly. Someone offering a “cash price” with no VAT mentioned is either working below the registration threshold or avoiding their tax obligations, and either way it signals a business you should approach carefully.

    What landlords and buy-to-let owners should know specifically

    Being a landlord comes with specific obligations around property maintenance, and external brickwork is part of that. Under the Landlord and Tenant Act 1985, landlords must keep the structure and exterior of a property in repair. Failing mortar that leads to damp internally is a direct breach of that obligation and can expose a landlord to enforcement action from the local council’s environmental health team, as well as compensation claims from tenants.

    For those investing in property through a buy-to-let portfolio, the calculus is straightforward. A repointing job costing £2,000 today averts potential damp remediation, structural repairs, and potential rental voids that could easily exceed £10,000 over the next decade. Lister Group, which offers lettings management alongside its mortgage and buy-to-let advisory services, regularly sees landlords across Nottinghamshire who have deferred maintenance for too long. Whether you’re moving house, taking on your first rental property, or expanding a portfolio, getting on top of external maintenance early is the kind of decision that protects asset value and keeps homeowners and tenants on the right side of the law.

    If you’re considering the wider costs of maintaining a home, it’s worth reading about how housing benefit rates are affecting private renters, which gives useful context on the financial pressures facing both landlords and tenants in 2026. And for homeowners thinking more broadly about property condition, our piece on what to check before committing to a purchase applies the same scrutiny to outdoor structures that you should bring to your main walls.

    Repointing is never glamorous. Nobody gets excited about mortar. But a well-pointed brick wall keeps water out, keeps the structure sound, and keeps your heating bills lower because damp walls lose heat faster. Sort it early, hire someone who knows what they’re doing, and specify the right mortar for your property. That’s genuinely all there is to it.

    Frequently Asked Questions

    How much does repointing a brick wall cost in the UK in 2026?

    Most homeowners in England pay between £25 and £55 per square metre for repointing, with a full front elevation on a semi-detached house typically costing £1,500 to £3,500. Chimney stacks start at around £400 to £800. Lime mortar adds a 20 to 30% premium over cement but is essential for older properties.

    How do I know if my mortar joints need repointing?

    Run your finger along the mortar joints; if material crumbles away or the joint has recessed more than 5mm from the brick face, repointing is needed. Damp patches that persist after rain and white efflorescence on the brickwork are also strong indicators that water is getting through deteriorated joints.

    What is the difference between lime mortar and cement mortar for repointing?

    Lime mortar is softer, breathable, and flexible, making it the correct choice for houses built before around 1920. Cement mortar is harder and cheaper but can cause bricks to spall (crack and break away) on older properties because it doesn’t flex with the wall. Historic England recommends lime-based mixes for pre-1920 buildings.

    Can I repoint brickwork myself, or should I hire a professional?

    Small areas on modern brick construction are manageable as a DIY job if you’re comfortable with the preparation and mixing. However, lime mortar requires more skill and careful temperature management, and any work on a listed building or in a conservation area should always be done by a qualified mason. For larger areas or older properties, hiring a professional is strongly advisable.

  • Why Britain’s Village and Town Carnivals Are Struggling to Find Volunteers, and What Happens If They Disappear

    Why Britain’s Village and Town Carnivals Are Struggling to Find Volunteers, and What Happens If They Disappear

    Every summer, in towns and villages across Britain, somebody puts up bunting. A committee of six or seven people, most of them in their sixties, books the brass band, argues about the raffle prizes, and hopes to God it doesn’t rain. British community carnivals have run on exactly this kind of stubborn, unglamorous goodwill for generations. But that goodwill is running out. The volunteers are ageing, the councils are cutting, and younger people aren’t stepping in. The result is that dozens of these events are quietly folding each year, with barely a mention in the local paper.

    Carnival float parade through a British town street — British community carnivals at their best
    Photo by Drinu Cutajar on Pexels

    The scale of the problem

    There’s no single national body that tracks how many community carnivals Britain loses each year, which is itself part of the problem. The Carnival Arts Network estimates there are around 5,000 community-run fairs, galas, and carnivals held across England, Scotland, and Wales annually, but that figure has been drifting downward for at least a decade. Local news sites occasionally note when a long-running event folds, the Melton Mowbray Carnival ran for 94 years before it stopped in 2023, the Ormskirk Carnival committee disbanded in 2024, but most disappear without any coverage at all. They just don’t happen one summer, and then the next, and eventually people stop expecting them.

    The funding picture is bleak. According to the Local Government Association, English councils have cut arts and culture spending by over 40% in real terms since 2010. Summer events and community festivals are rarely ring-fenced and often first to go when budgets tighten. A carnival that once received a £3,000 grant from its district council now gets nothing, meaning the organising committee has to find that money through sponsorship or ticket sales, tasks that require skills and time most ageing volunteer committees simply don’t have.

    Who actually runs these things?

    I spoke to a woman in her early seventies who has chaired a town carnival committee in the East Midlands for eighteen years. She asked not to be named because she didn’t want to embarrass her council, but her account was striking. Her committee has nine members. The youngest is fifty-four. They’ve tried recruiting younger people through Facebook posts, through the local school, even through the parish newsletter. One person in their thirties came to two meetings and didn’t come back. “They’ve got kids, they’ve got jobs, they’ve got a lot on,” she said. “I understand it. But somebody has to do this.”

    The time commitment is real. Running a decent-sized community carnival, float procession, fair rides, stage acts, food stalls, requires roughly 400 hours of committee work spread across the year. Insurance alone can run to £2,500. There’s the health and safety plan, the road closure application, the negotiations with the fairground operator, the sponsorship letters, the social media. That last one is increasingly a problem: the platforms have changed, the algorithms have changed, and a committee that built its audience on Facebook over a decade is now finding that Facebook shows their posts to almost nobody.

    Volunteer committee planning a British community carnival around a table
    Photo by Mohammed Amine Jaddari on Pexels

    What these events actually do for a community

    It’s easy to romanticise carnivals and summer fairs as a kind of warm, sepia-tinted Britishness. But the case for them isn’t nostalgic, it’s practical. Research from Nesta and various community wellbeing studies consistently shows that shared public events, particularly free or low-cost ones, are among the most effective tools for reducing social isolation. When a carnival draws 3,000 people onto a town’s park on a Saturday afternoon, it creates connections that wouldn’t otherwise happen. The elderly man who watches the parade from his garden gate. The family new to the area who talks to someone for the first time. The teenager who helps on a stall and realises they like doing things.

    Strip those events away and what fills the gap? Not much, is my honest answer. The high street is already struggling, as with sport, the economics of community participation keep narrowing, and commercial leisure is expensive. A summer fair with free entry is one of the last genuinely accessible public events many communities have. When it goes, nothing replaces it.

    The digital turn: helping some, not most

    There’s a counternarrative worth acknowledging. Some carnivals and fairs have found a second life online. Short videos of carnival processions, particularly those with elaborate floats or steel bands, perform surprisingly well on social media. A handful of committee chairs have discovered that posting behind-the-scenes content, the chaos of setting up, the rain damage on the floats, the last-minute scramble for volunteers, generates genuine engagement. If you’re curious about that phenomenon, there’s a longer read on the village fête organisers who accidentally went viral: how britain’s most quintessentially local events are finding a national audience, which captures the peculiar warmth people feel toward these events even when they’ve never attended one.

    But I’d be careful not to overstate this. Going viral on TikTok doesn’t pay for public liability insurance. A few thousand views doesn’t fill a volunteer rota. The digital success stories are real but rare. For every carnival committee that figures out how to reach new audiences online, there are twenty that fold because nobody under sixty has the bandwidth to show up to a planning meeting on a Tuesday evening in February.

    What could actually help

    The fixes being discussed in the voluntary and community sector aren’t dramatic. The most commonly cited are: longer-term small grants (rather than one-year funding that forces committees to apply every twelve months), council support with bureaucracy like road closure applications and insurance procurement, and structured volunteer recruitment through schools and universities as part of community engagement programmes.

    Some areas are trying community interest companies as an alternative to the traditional unincorporated committee model, which can make it easier to take on paid part-time coordinators. A few larger carnivals have brought in professional event management help for one or two key tasks, freeing the volunteer core to focus on what they know. None of these solutions are glamorous. They’re just sensible.

    The funding squeeze on grassroots community activity isn’t unique to athletics or sport, it runs through every corner of British community life, and carnivals are one of its less-noticed casualties. If you’ve ever stood on a pavement watching a carnival float go past and felt something warm about where you live, it’s worth knowing that feeling depends on a small group of exhausted volunteers and a grant application that might not come through next year. That’s not a reason for despair. It is, though, a reason to pay attention.

  • How the BBC Licence Fee Freeze Is Quietly Changing What British Audiences Actually Watch

    How the BBC Licence Fee Freeze Is Quietly Changing What British Audiences Actually Watch

    Something is shifting at the BBC, and it is happening quietly enough that most people haven’t noticed yet. The prolonged licence fee freeze, which has held the annual fee at £169.50 since April 2024, has been eating into the corporation’s real-terms budget every year. Inflation does the rest. By most independent estimates, the BBC has lost somewhere between £200 million and £300 million in purchasing power since the freeze began. That is not an abstract figure, it translates directly into fewer commissions, smaller production budgets, and a steady narrowing of what ends up on your television screen. The consequences of BBC licence fee cuts 2026 are already visible if you know where to look.

    Empty BBC television studio interior illustrating the BBC licence fee cuts 2026 production pressures
    Photo by Dominika Poláková on Pexels

    What the licence fee freeze actually means in practice

    The government extended the freeze on the licence fee as part of the 2022 settlement, pegging it for two years then allowing only modest increases well below the rate of inflation. In real terms, that is a cut. The BBC’s own annual reports have acknowledged the pressure, and the organisation has responded with rounds of redundancies across news, regional broadcasting and drama departments. In 2025 alone, more than 500 jobs went, with BBC News bearing much of the pain.

    What viewers tend not to see is the quieter stuff: the drama series that gets four episodes instead of six, the arts documentary strand that loses its slot, the local radio programme that merges with a regional equivalent. These aren’t headline closures. They are incremental reductions that compound over time until you realise a channel feels thinner than it once did.

    The BBC’s own figures, published in its annual report, show that total content spend as a proportion of revenue has been declining since 2021. Drama and entertainment have taken the sharpest cuts. Factual and news have held up slightly better, though staffing reductions in those areas tell a different story.

    Co-productions are filling the gap, but at a cost

    One response to squeezed budgets has been a surge in co-production deals with overseas broadcasters. Working with HBO, Netflix, Apple TV+ or Scandinavian public broadcasters allows the BBC to make expensive programmes it could no longer fund alone. The trouble is that co-production always involves compromise. The overseas partner has its own audience to consider, its own editorial preferences, and often a financial stake that gives it real influence over creative decisions.

    I’ve watched this play out with a number of high-profile series. Productions that might once have been unambiguously British in setting, tone and perspective now carry a slight international gloss, engineered to travel well across markets. That’s not always a bad thing, but it does mean the BBC is making fewer programmes that are purely for and about Britain. The kind of drama that used to define the corporation, gritty, regional, specific, sometimes difficult, is harder to justify when you need a co-producer in Baltimore or Stockholm to say yes.

    The BBC has been open about its co-production strategy in public statements, framing it as creative partnership rather than financial necessity. My reading of the situation is that it is primarily the latter, dressed up in the language of the former. When you are short of money, you find partners who have it. That’s rational. But British audiences should understand what they are getting in return.

    The push towards iPlayer and what it means for older or rural viewers

    Alongside the content cuts, the BBC has been aggressively redirecting audiences towards iPlayer. The strategy makes sense commercially: streaming platforms generate data, attract younger demographics, and offer the kind of on-demand flexibility that linear television no longer can. BBC iPlayer has grown considerably, with the corporation reporting record usage figures throughout 2025.

    But the iPlayer pivot carries a real cost for a significant portion of the BBC’s audience. Around 1.9 million households in the UK still have no fixed broadband connection, according to Ofcom data, and rural areas remain badly underserved. For older viewers who rely on Freeview or Freesat, the gradual withdrawal of linear scheduling in favour of streaming-first releases creates a genuine access problem. A drama that drops all episodes on iPlayer simultaneously is effectively invisible to anyone who watches television in the traditional sense.

    There is also the question of what streaming-first commissioning does to the texture of British television. The scheduled evening programme, watched by millions at the same time, creates a shared cultural moment in a way that on-demand never quite replicates. That communal dimension matters, and it erodes slowly as more content moves behind the streaming interface.

    For context, this pattern of access and exclusion echoes other debates in British public life. The argument over free-to-air television rights in women’s football follows a similar logic: when content moves away from open broadcast towards subscription or streaming platforms, it tends to reach a narrower, wealthier and younger audience.

    What British viewers actually stand to lose

    The BBC’s public service obligations remain written into its royal charter, but charter commitments are broad, and the practical expression of them depends on money. Regional programming is the most vulnerable category. BBC Scotland, BBC Wales and BBC Northern Ireland have all seen budget pressure, and local news, which serves communities that commercial broadcasters will never find profitable, is being quietly reduced in scope.

    Children’s television is another area of concern. CBBC and CBeebies have faced cuts across the board, with a greater proportion of content now acquired from independent producers rather than made in-house. The BBC’s historic investment in British children’s content, which has been a genuine point of cultural pride and practical value for generations, is shrinking.

    Sport is also feeling the effect. The BBC can no longer compete for premium rights at the prices that Sky and TNT Sports pay. Its sports coverage increasingly relies on events it already holds rights to by tradition, Wimbledon, the Olympics, the FA Cup, and even some of those have been subject to pressure. The wider conversation about access to sport on free-to-air television, which I’ve looked at before in the context of how ordinary fans are being priced out of football entirely, applies to broadcast rights just as much as match tickets.

    Perhaps most significantly, the BBC’s ability to take editorial and creative risks is diminishing. Expensive, slow-burn, difficult drama, the kind that might not find an immediate audience but builds a cultural legacy, requires a broadcaster willing to back it without needing a guaranteed return. That is precisely what a well-funded public broadcaster is supposed to do, and it is precisely what becomes harder when budgets tighten year after year.

    Is there a realistic fix?

    The licence fee model is genuinely under pressure and has been for years. Younger audiences who consume all their content through streaming services are reluctant to pay a flat fee for a broadcaster they rarely watch on a traditional set. The BBC has acknowledged this, and the government’s 2027 charter review will likely force a reckoning with the funding model itself.

    Possible options include a subscription model, a broader household levy tied to broadband, or continued licence fee increases linked to inflation. Each carries its own problems. A subscription model risks turning the BBC into just another streamer, competing on the same terms as Netflix with none of the public service purpose. A broadband levy extends the reach but raises questions about universality. And a proper inflation-linked increase would require political will that has been conspicuously absent.

    In the meantime, the cuts continue, the co-production deals multiply, and the BBC quietly reshapes itself around a streaming audience it can measure and a linear audience it is gradually letting drift. British viewers are losing something real, and the slow erosion of traditional British media is a pattern playing out across more than one institution. Whether the BBC that emerges from this period still feels like a genuine public broadcaster, or just another content platform with a heritage brand attached, depends on decisions being made right now.

    Frequently Asked Questions

    What is the current BBC licence fee in 2026?

    The BBC licence fee is £169.50 per year in 2026. It has been subject to a prolonged freeze that has seen its real-terms value decline significantly due to inflation since the settlement began in 2022.

    What programmes has the BBC cut because of the licence fee freeze?

    The BBC has cut roles across news, regional broadcasting, drama and entertainment, with more than 500 jobs lost in 2025. Individual programme cuts are less publicised but include reduced episode orders, merged regional radio output and scaled-back children’s television commissions.

    Why is the BBC making more co-productions with overseas broadcasters?

    Co-productions allow the BBC to share the cost of expensive programmes with international partners such as HBO or Scandinavian public broadcasters. With the real-terms budget shrinking due to the licence fee freeze, co-productions have become a financial necessity rather than a purely creative choice.