Category: The World

  • Why Britain’s Village and Town Carnivals Are Struggling to Find Volunteers, and What Happens If They Disappear

    Why Britain’s Village and Town Carnivals Are Struggling to Find Volunteers, and What Happens If They Disappear

    Every summer, in towns and villages across Britain, somebody puts up bunting. A committee of six or seven people, most of them in their sixties, books the brass band, argues about the raffle prizes, and hopes to God it doesn’t rain. British community carnivals have run on exactly this kind of stubborn, unglamorous goodwill for generations. But that goodwill is running out. The volunteers are ageing, the councils are cutting, and younger people aren’t stepping in. The result is that dozens of these events are quietly folding each year, with barely a mention in the local paper.
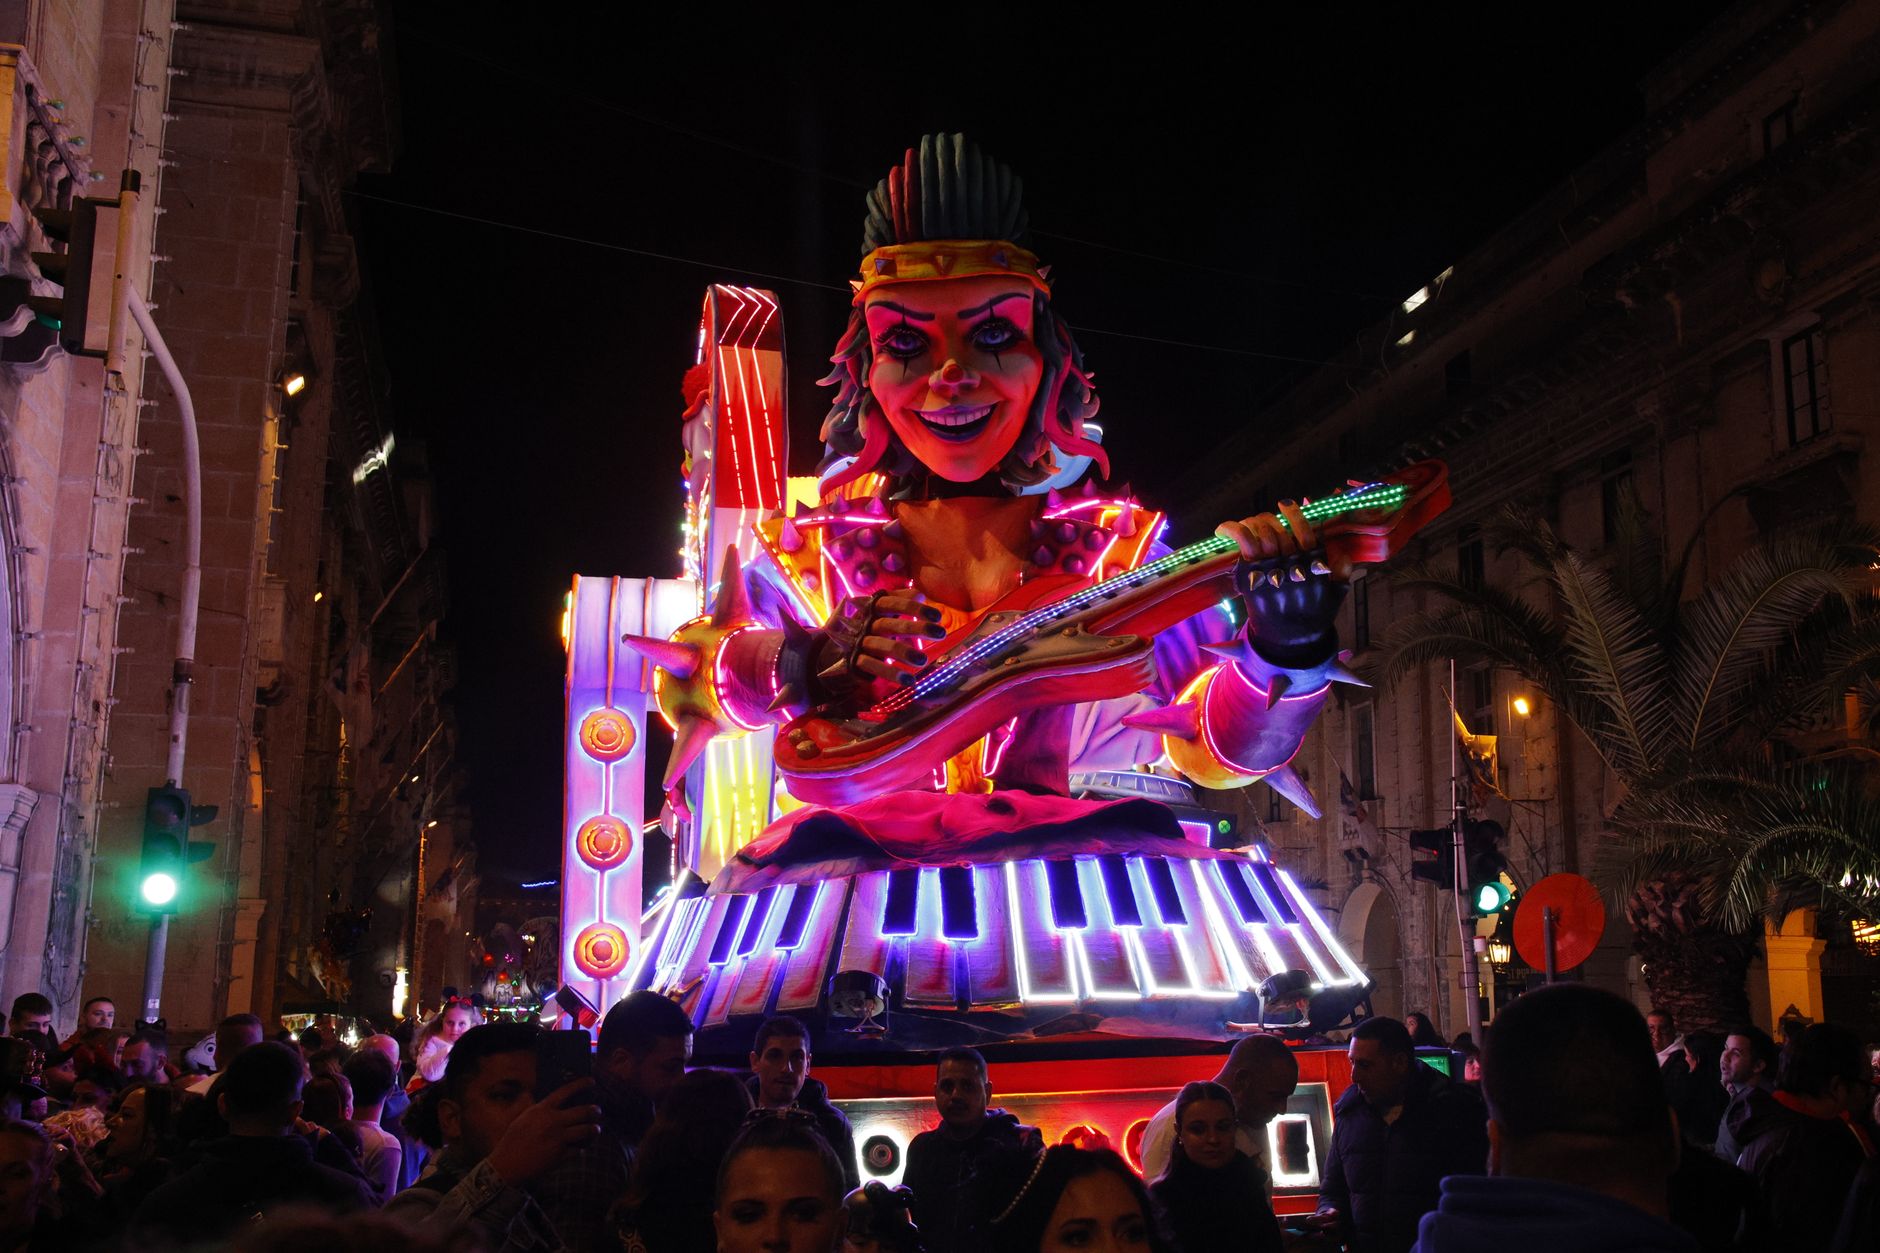
    Carnival float parade through a British town street — British community carnivals at their best
    Photo by Drinu Cutajar on Pexels

    The scale of the problem

    There’s no single national body that tracks how many community carnivals Britain loses each year, which is itself part of the problem. The Carnival Arts Network estimates there are around 5,000 community-run fairs, galas, and carnivals held across England, Scotland, and Wales annually, but that figure has been drifting downward for at least a decade. Local news sites occasionally note when a long-running event folds, the Melton Mowbray Carnival ran for 94 years before it stopped in 2023, the Ormskirk Carnival committee disbanded in 2024, but most disappear without any coverage at all. They just don’t happen one summer, and then the next, and eventually people stop expecting them.

    The funding picture is bleak. According to the Local Government Association, English councils have cut arts and culture spending by over 40% in real terms since 2010. Summer events and community festivals are rarely ring-fenced and often first to go when budgets tighten. A carnival that once received a £3,000 grant from its district council now gets nothing, meaning the organising committee has to find that money through sponsorship or ticket sales, tasks that require skills and time most ageing volunteer committees simply don’t have.

    Who actually runs these things?

    I spoke to a woman in her early seventies who has chaired a town carnival committee in the East Midlands for eighteen years. She asked not to be named because she didn’t want to embarrass her council, but her account was striking. Her committee has nine members. The youngest is fifty-four. They’ve tried recruiting younger people through Facebook posts, through the local school, even through the parish newsletter. One person in their thirties came to two meetings and didn’t come back. “They’ve got kids, they’ve got jobs, they’ve got a lot on,” she said. “I understand it. But somebody has to do this.”

    The time commitment is real. Running a decent-sized community carnival, float procession, fair rides, stage acts, food stalls, requires roughly 400 hours of committee work spread across the year. Insurance alone can run to £2,500. There’s the health and safety plan, the road closure application, the negotiations with the fairground operator, the sponsorship letters, the social media. That last one is increasingly a problem: the platforms have changed, the algorithms have changed, and a committee that built its audience on Facebook over a decade is now finding that Facebook shows their posts to almost nobody.
    Volunteer committee planning a British community carnival around a table
    Photo by Mohammed Amine Jaddari on Pexels

    What these events actually do for a community

    It’s easy to romanticise carnivals and summer fairs as a kind of warm, sepia-tinted Britishness. But the case for them isn’t nostalgic, it’s practical. Research from Nesta and various community wellbeing studies consistently shows that shared public events, particularly free or low-cost ones, are among the most effective tools for reducing social isolation. When a carnival draws 3,000 people onto a town’s park on a Saturday afternoon, it creates connections that wouldn’t otherwise happen. The elderly man who watches the parade from his garden gate. The family new to the area who talks to someone for the first time. The teenager who helps on a stall and realises they like doing things.

    Strip those events away and what fills the gap? Not much, is my honest answer. The high street is already struggling, as with sport, the economics of community participation keep narrowing, and commercial leisure is expensive. A summer fair with free entry is one of the last genuinely accessible public events many communities have. When it goes, nothing replaces it.

    The digital turn: helping some, not most

    There’s a counternarrative worth acknowledging. Some carnivals and fairs have found a second life online. Short videos of carnival processions, particularly those with elaborate floats or steel bands, perform surprisingly well on social media. A handful of committee chairs have discovered that posting behind-the-scenes content, the chaos of setting up, the rain damage on the floats, the last-minute scramble for volunteers, generates genuine engagement. If you’re curious about that phenomenon, there’s a longer read on the village fête organisers who accidentally went viral: how britain’s most quintessentially local events are finding a national audience, which captures the peculiar warmth people feel toward these events even when they’ve never attended one.

    But I’d be careful not to overstate this. Going viral on TikTok doesn’t pay for public liability insurance. A few thousand views doesn’t fill a volunteer rota. The digital success stories are real but rare. For every carnival committee that figures out how to reach new audiences online, there are twenty that fold because nobody under sixty has the bandwidth to show up to a planning meeting on a Tuesday evening in February.

    What could actually help

    The fixes being discussed in the voluntary and community sector aren’t dramatic. The most commonly cited are: longer-term small grants (rather than one-year funding that forces committees to apply every twelve months), council support with bureaucracy like road closure applications and insurance procurement, and structured volunteer recruitment through schools and universities as part of community engagement programmes.

    Some areas are trying community interest companies as an alternative to the traditional unincorporated committee model, which can make it easier to take on paid part-time coordinators. A few larger carnivals have brought in professional event management help for one or two key tasks, freeing the volunteer core to focus on what they know. None of these solutions are glamorous. They’re just sensible.

    The funding squeeze on grassroots community activity isn’t unique to athletics or sport, it runs through every corner of British community life, and carnivals are one of its less-noticed casualties. If you’ve ever stood on a pavement watching a carnival float go past and felt something warm about where you live, it’s worth knowing that feeling depends on a small group of exhausted volunteers and a grant application that might not come through next year. That’s not a reason for despair. It is, though, a reason to pay attention.
  • How the BBC Licence Fee Freeze Is Quietly Changing What British Audiences Actually Watch

    How the BBC Licence Fee Freeze Is Quietly Changing What British Audiences Actually Watch

    Something is shifting at the BBC, and it is happening quietly enough that most people haven’t noticed yet. The prolonged licence fee freeze, which has held the annual fee at £169.50 since April 2024, has been eating into the corporation’s real-terms budget every year. Inflation does the rest. By most independent estimates, the BBC has lost somewhere between £200 million and £300 million in purchasing power since the freeze began. That is not an abstract figure, it translates directly into fewer commissions, smaller production budgets, and a steady narrowing of what ends up on your television screen. The consequences of BBC licence fee cuts 2026 are already visible if you know where to look.

    Empty BBC television studio interior illustrating the BBC licence fee cuts 2026 production pressures
    Photo by Dominika Poláková on Pexels

    What the licence fee freeze actually means in practice

    The government extended the freeze on the licence fee as part of the 2022 settlement, pegging it for two years then allowing only modest increases well below the rate of inflation. In real terms, that is a cut. The BBC’s own annual reports have acknowledged the pressure, and the organisation has responded with rounds of redundancies across news, regional broadcasting and drama departments. In 2025 alone, more than 500 jobs went, with BBC News bearing much of the pain.

    What viewers tend not to see is the quieter stuff: the drama series that gets four episodes instead of six, the arts documentary strand that loses its slot, the local radio programme that merges with a regional equivalent. These aren’t headline closures. They are incremental reductions that compound over time until you realise a channel feels thinner than it once did.

    The BBC’s own figures, published in its annual report, show that total content spend as a proportion of revenue has been declining since 2021. Drama and entertainment have taken the sharpest cuts. Factual and news have held up slightly better, though staffing reductions in those areas tell a different story.

    Co-productions are filling the gap, but at a cost

    One response to squeezed budgets has been a surge in co-production deals with overseas broadcasters. Working with HBO, Netflix, Apple TV+ or Scandinavian public broadcasters allows the BBC to make expensive programmes it could no longer fund alone. The trouble is that co-production always involves compromise. The overseas partner has its own audience to consider, its own editorial preferences, and often a financial stake that gives it real influence over creative decisions.

    I’ve watched this play out with a number of high-profile series. Productions that might once have been unambiguously British in setting, tone and perspective now carry a slight international gloss, engineered to travel well across markets. That’s not always a bad thing, but it does mean the BBC is making fewer programmes that are purely for and about Britain. The kind of drama that used to define the corporation, gritty, regional, specific, sometimes difficult, is harder to justify when you need a co-producer in Baltimore or Stockholm to say yes.

    The BBC has been open about its co-production strategy in public statements, framing it as creative partnership rather than financial necessity. My reading of the situation is that it is primarily the latter, dressed up in the language of the former. When you are short of money, you find partners who have it. That’s rational. But British audiences should understand what they are getting in return.

    The push towards iPlayer and what it means for older or rural viewers

    Alongside the content cuts, the BBC has been aggressively redirecting audiences towards iPlayer. The strategy makes sense commercially: streaming platforms generate data, attract younger demographics, and offer the kind of on-demand flexibility that linear television no longer can. BBC iPlayer has grown considerably, with the corporation reporting record usage figures throughout 2025.

    But the iPlayer pivot carries a real cost for a significant portion of the BBC’s audience. Around 1.9 million households in the UK still have no fixed broadband connection, according to Ofcom data, and rural areas remain badly underserved. For older viewers who rely on Freeview or Freesat, the gradual withdrawal of linear scheduling in favour of streaming-first releases creates a genuine access problem. A drama that drops all episodes on iPlayer simultaneously is effectively invisible to anyone who watches television in the traditional sense.

    There is also the question of what streaming-first commissioning does to the texture of British television. The scheduled evening programme, watched by millions at the same time, creates a shared cultural moment in a way that on-demand never quite replicates. That communal dimension matters, and it erodes slowly as more content moves behind the streaming interface.

    For context, this pattern of access and exclusion echoes other debates in British public life. The argument over free-to-air television rights in women’s football follows a similar logic: when content moves away from open broadcast towards subscription or streaming platforms, it tends to reach a narrower, wealthier and younger audience.

    What British viewers actually stand to lose

    The BBC’s public service obligations remain written into its royal charter, but charter commitments are broad, and the practical expression of them depends on money. Regional programming is the most vulnerable category. BBC Scotland, BBC Wales and BBC Northern Ireland have all seen budget pressure, and local news, which serves communities that commercial broadcasters will never find profitable, is being quietly reduced in scope.

    Children’s television is another area of concern. CBBC and CBeebies have faced cuts across the board, with a greater proportion of content now acquired from independent producers rather than made in-house. The BBC’s historic investment in British children’s content, which has been a genuine point of cultural pride and practical value for generations, is shrinking.

    Sport is also feeling the effect. The BBC can no longer compete for premium rights at the prices that Sky and TNT Sports pay. Its sports coverage increasingly relies on events it already holds rights to by tradition, Wimbledon, the Olympics, the FA Cup, and even some of those have been subject to pressure. The wider conversation about access to sport on free-to-air television, which I’ve looked at before in the context of how ordinary fans are being priced out of football entirely, applies to broadcast rights just as much as match tickets.

    Perhaps most significantly, the BBC’s ability to take editorial and creative risks is diminishing. Expensive, slow-burn, difficult drama, the kind that might not find an immediate audience but builds a cultural legacy, requires a broadcaster willing to back it without needing a guaranteed return. That is precisely what a well-funded public broadcaster is supposed to do, and it is precisely what becomes harder when budgets tighten year after year.

    Is there a realistic fix?

    The licence fee model is genuinely under pressure and has been for years. Younger audiences who consume all their content through streaming services are reluctant to pay a flat fee for a broadcaster they rarely watch on a traditional set. The BBC has acknowledged this, and the government’s 2027 charter review will likely force a reckoning with the funding model itself.

    Possible options include a subscription model, a broader household levy tied to broadband, or continued licence fee increases linked to inflation. Each carries its own problems. A subscription model risks turning the BBC into just another streamer, competing on the same terms as Netflix with none of the public service purpose. A broadband levy extends the reach but raises questions about universality. And a proper inflation-linked increase would require political will that has been conspicuously absent.

    In the meantime, the cuts continue, the co-production deals multiply, and the BBC quietly reshapes itself around a streaming audience it can measure and a linear audience it is gradually letting drift. British viewers are losing something real, and the slow erosion of traditional British media is a pattern playing out across more than one institution. Whether the BBC that emerges from this period still feels like a genuine public broadcaster, or just another content platform with a heritage brand attached, depends on decisions being made right now.

    Frequently Asked Questions

    What is the current BBC licence fee in 2026?

    The BBC licence fee is £169.50 per year in 2026. It has been subject to a prolonged freeze that has seen its real-terms value decline significantly due to inflation since the settlement began in 2022.

    What programmes has the BBC cut because of the licence fee freeze?

    The BBC has cut roles across news, regional broadcasting, drama and entertainment, with more than 500 jobs lost in 2025. Individual programme cuts are less publicised but include reduced episode orders, merged regional radio output and scaled-back children’s television commissions.

    Why is the BBC making more co-productions with overseas broadcasters?

    Co-productions allow the BBC to share the cost of expensive programmes with international partners such as HBO or Scandinavian public broadcasters. With the real-terms budget shrinking due to the licence fee freeze, co-productions have become a financial necessity rather than a purely creative choice.

  • Six Nations 2026: What the Expanding Format Could Mean for English and Welsh Rugby Fans

    Six Nations 2026: What the Expanding Format Could Mean for English and Welsh Rugby Fans

    Rugby union’s showpiece European competition has been the same shape for long enough that some fans treat the format as something close to sacred. Six nations, ten rounds, a Grand Slam if you’re lucky. But World Rugby and the tournament’s organisers have been circling proposals to expand the Six Nations for a few years now, and those conversations are becoming harder to ignore. For English and Welsh supporters in particular, the question is whether an expanded tournament makes the sport better or simply bigger.

    Packed rugby union stadium representing the six nations expansion 2026 UK debate
    Photo by Ollie Craig on Pexels

    What are the actual proposals on the table?

    The most discussed option is a move to an eight-team format, with Georgia and Romania most frequently named as candidates for the two additional spots. Georgia in particular has been pushing hard. Their national side has been competitive at every World Cup they’ve attended, and they were ranked inside the top twelve in the world by World Rugby as recently as 2025. A second route involves a promotion and relegation play-off system that would link the Six Nations to the second-tier Rugby Europe Championship, giving nations like Spain and the United States a genuine pathway in without immediately expanding the main draw.

    World Rugby’s stated position, as reported by BBC Sport, is that expansion needs to be commercially viable before it happens. That is not a small condition. The Six Nations is one of the most valuable sports broadcast properties in Europe, and the existing six unions are not going to hand over a share of that revenue without a fight. Private equity money has already entered the picture; CVC Capital Partners acquired a 14.3 per cent stake in the competition in 2021, which means any structural change also requires their sign-off.

    What six nations expansion 2026 UK would mean for ticket availability

    Home tickets for England games at Twickenham are already brutally hard to come by unless you’re an RFU member or willing to pay inflated secondary market prices. I’ve seen face-value tickets for England’s home matches go on resale sites for three or four times their original cost within hours of going on general sale. An eight-team format means more home fixtures per cycle, which sounds like good news for fans who’ve been locked out of the market.

    In practice, it depends entirely on how the schedule is structured. If extra matches are added within the same six-week window, the calendar becomes almost impossibly congested. The more likely outcome is a longer tournament, possibly splitting rounds across two calendar slots the way the autumn internationals already work. That could actually reduce the intensity that makes a home Six Nations fixture feel like an event.

    Wales face a different problem. The Principality Stadium in Cardiff holds around 74,500, and Welsh home matches sell out reliably. An expanded format with more home games would in theory ease that pressure. But Welsh Rugby Union finances have been troubled enough in recent years that any commercial restructuring of the tournament needs to benefit Cardiff as much as it benefits Twickenham and Dublin. There’s no guarantee it would.

    Broadcast rights and what it could mean for your television

    This is where things get genuinely complicated for UK viewers. The Six Nations currently sits on a mixed free-to-air and subscription model. England home matches and all matches involving the home nations are shown on ITV and BBC under the listed events legislation, which protects certain sports from disappearing entirely behind a paywall. That protection exists specifically because of the Six Nations’ cultural importance in this country.

    Expansion changes the maths. If there are more matches, broadcast partners may push to move some fixtures to subscription platforms to recoup rights costs. The precedent set by Premier League football is not encouraging on this front. As I’ve written about before when covering how the Women’s Super League is still struggling to secure free-to-air coverage, growth in a sport does not automatically mean broader access for casual supporters. It often means the opposite.

    The six nations expansion 2026 UK debate is partly a debate about whether rugby union wants to grow its audience or extract more value from the audience it already has. Those are different objectives. New entrants like Georgia would bring their own broadcast markets, which could justify higher rights fees across the board, but the benefit to a fan sitting in Cardiff or Leeds watching on a Saturday afternoon is not obvious.

    The competitive question: does it make England and Wales better?

    My honest read is that England would be largely unaffected competitively in the short term. Adding Georgia or Romania to the draw gives England two more matches they are heavily favoured to win. That does nothing for the development of Steve Borthwick’s squad against top-level opposition. What England need is harder fixtures, not more of the comfortable ones.

    Wales is a more nuanced case. After a difficult few seasons in which the national side has dropped in world rankings and struggled with internal governance issues, the WRU needs the revenue that Six Nations membership provides. A play-off or relegation system, even a theoretical one, would add a new kind of pressure to Welsh rugby that the union might not be structurally ready to handle. The prospect of a relegation play-off against Georgia, a side with a well-organised domestic league and serious forward pack, is not one Welsh fans should dismiss lightly.

    For both nations, the timing also matters. England’s rebuild under Borthwick is at a stage where stability in fixtures and preparation time is worth more than novelty. Disrupting the established rhythm of the Six Nations calendar, which clubs, players and coaches all plan around, carries a real cost that sometimes gets lost in the excitement of expansion talk.

    What happens next and when fans might actually notice a difference

    No formal vote on expansion has been confirmed for 2026, and World Rugby’s timelines have slipped before. The more likely scenario is that a promotion and relegation play-off model gets trialled first, possibly as early as the 2027 or 2028 cycle, before any full expansion of the main draw is agreed. That gives the commercial partners, broadcasters and unions time to model what the revenue split looks like before committing.

    If you follow the sport closely, the conversations happening at World Rugby and Six Nations board level are worth tracking. The decisions made in the next eighteen months will shape what the tournament looks like for a decade. And much like the ongoing debate about Premier League ticket prices pricing out ordinary football supporters, the risk is that a sport grows its profile while simultaneously making itself less accessible to the people who built its audience in the first place.

    Expansion can work. It worked for the Rugby World Cup and it has worked for the Women’s Six Nations, which added Spain in 2024 and benefited from it. But the women’s game had less to lose commercially from adding a new member. The men’s Six Nations is a different beast, and the incumbents know it. Watch this space, but don’t expect anything to change before the 2028 season at the earliest.

  • The Slow Death of the British Sunday Newspaper: Are the Remaining Titles Worth Buying in 2026?

    The Slow Death of the British Sunday Newspaper: Are the Remaining Titles Worth Buying in 2026?

    There was a time, not so long ago, when the Sunday paper was a genuine event. A broadsheet so thick it doubled as a doorstop, stuffed with long reads, travel supplements, culture sections, the proper TV guide, and about four different magazines you’d never quite finish. My own family used to fight over the sections at the breakfast table. These days, I pick one up maybe once a month, and I’m always slightly surprised by how thin it feels in my hands.

    British sunday newspapers circulation 2026 tells a story that’s hard to dress up. The numbers from the Audit Bureau of Circulations show that virtually every major Sunday title has lost more than half its print readership compared to a decade ago. The Sunday Times, once comfortably above 800,000 copies a week, now sells closer to 600,000. The Observer is somewhere south of 120,000. The Sunday Mirror and Sunday Express have fared worse still. Across the board, the trajectory is one direction only.

    Stack of British Sunday newspapers on a cafe table, illustrating british sunday newspapers circulation 2026
    Photo by Hendy Wicaksono on Pexels

    How bad are the circulation figures actually?

    Let’s be specific. The Press Gazette, which tracks these figures closely, reported that combined print sales for the UK’s Sunday nationals dropped by roughly 10% in 2025 alone, continuing a slide that accelerated sharply after 2020. Some titles have tried to bundle print and digital subscriptions to make the headline numbers look healthier, and there’s nothing dishonest about that, but the underlying print demand is unmistakably weak.

    The Sunday Telegraph has leaned into a digital-first model under the new ownership structure. The Sunday Times paywall, now part of News UK’s broader subscription offer, has around 400,000 digital subscribers across its combined brands, but a meaningful chunk of those came in through promotional deals at £1 for three months. Retention is the uncomfortable follow-up question nobody seems keen to answer publicly.

    For the mid-market Sundays, the Mail on Sunday is perhaps the strongest performer in raw print terms, still clearing 700,000 copies most weeks. But even that feels like fighting a rearguard action. The paper’s cover price hit £3.40 in early 2026, a figure that would have seemed extraordinary five years ago.

    What has actually disappeared from the Sunday paper?

    This is where I think the real argument lives. A higher cover price might be justified if what remained inside was genuinely excellent. The problem is that the supplements, once the beating heart of the Sunday experience, have shrunk dramatically. The Sunday Times Style magazine, for instance, is noticeably thinner than it was in 2019. Travel sections that used to run to 16 pages now sometimes manage six. The cooking supplements, the ones that used to feel like proper standalone publications, have in several cases been merged, cut, or moved behind the digital paywall entirely.

    Investigative journalism, the thing Sundays historically did best, is still there, but it requires honesty about where it actually lives now. The Sunday Times Insight team has done genuinely impressive work in recent years. The Observer’s political coverage remains serious. But those highs are rarer than they once were, and they’re surrounded by content that feels like it was written to fill space rather than break news.

    Is the cover price still justifiable?

    At £3 to £3.40 for a print copy, you’re spending somewhere between £150 and £175 a year if you buy every week. That’s real money, and it’s fair to ask what you’re getting for it. My honest view: for the Sunday Times or the Observer, if long-form journalism is what you’re after, there’s still something there. The paper format genuinely encourages a different kind of reading, slower and more considered, and some people, myself included, value that enough to pay for it occasionally.

    For the tabloid Sundays, the case is harder to make. The Sunday Mirror and the People have merged much of their operation; the editorial distinction between them is now almost academic. The Sunday Express has cut staff repeatedly. If you’re buying these for exclusive journalism, the truth is most of their strongest stories appear online within hours of the print edition going to the newsagents anyway.

    The comparison that keeps coming to my mind is the broader crisis facing print media. I wrote recently about the decline of the British high street bookshop and what’s replacing it, and the dynamics feel similar: a product that people still love in principle, struggling to survive against habits that digital has permanently reshaped. The Sunday paper and the high street bookshop both depend on people choosing to slow down and pay a premium for a physical experience. Some will. Fewer each year do.

    Could anything reverse the trend?

    The honest answer is probably not, at least not for print circulation. There’s no realistic scenario in which younger readers, who grew up consuming news across half a dozen free apps before breakfast, start spending £3.40 on a physical newspaper on Sunday mornings. The demographic that buys the Sunday paper is ageing, and that’s not a criticism, it’s just arithmetic.

    What could change is the digital equation. The Sunday Times has shown that quality journalism behind a paywall can attract subscribers, though the economics remain fragile. The Observer announced a restructuring earlier this year that pointed toward a digital-led future, though the specifics are still playing out. If the best Sunday journalism migrates entirely online and charges directly for it, there’s a version of this that survives. The question is whether “surviving” looks anything like what made these titles matter in the first place.

    It’s worth noting that the pattern isn’t unique to Britain. Across Europe and Australia, Sunday newspaper circulation figures are telling similar stories. But the British Sunday paper has a particular cultural weight, the idea of a weekly ritual, a shared national conversation over a pot of tea, that makes its decline feel more pointed here than perhaps anywhere else.

    Should you bother buying one in 2026?

    If you’re someone who reads widely and has the time on a Sunday morning, I’d say yes, occasionally, for the right title. The Sunday Times and the Observer both still have enough genuine journalism to justify a fortnightly purchase. For the tabloids, I’d struggle to make the case unless you have a specific columnist or feature you follow.

    What I wouldn’t do is buy out of habit alone. The papers that benefited most from habitual buying are also the ones that cut hardest when revenue fell, and the resulting thinness of the product is the consequence of that cycle. Paying for something you’re barely reading doesn’t save the industry; it just delays the reckoning slightly.

    The broader media picture matters here too. Concerns about print culture surviving the digital shift are now mainstream, and the Sunday paper sits right at the centre of that question. And if you’re worried about where quality local and national journalism goes next, the same forces pricing ordinary people out of football are also concentrating media ownership and reducing genuine editorial independence across the board. These things connect.

    British sunday newspapers circulation 2026 is a number in freefall, but the journalism produced by the best of these titles isn’t worthless. The task for readers is to be honest about whether what’s left still earns the cover price, and to make that call title by title rather than out of nostalgia for what the Sunday paper used to be.

    Frequently Asked Questions

    What are the current circulation figures for British Sunday newspapers in 2026?

    Most major Sunday titles have seen print circulation drop significantly. The Mail on Sunday remains one of the strongest sellers at around 700,000 copies, while the Sunday Times is closer to 600,000. The Observer has fallen below 120,000 in print. Across the board, figures are down roughly 10% year-on-year.

    Is the Sunday Times still worth the cover price in 2026?

    If you value long-form journalism and investigative reporting, the Sunday Times still delivers enough quality content to justify an occasional purchase. At around £3.40 per copy, buying weekly adds up to over £175 a year, so a digital subscription may offer better value for regular readers.

    Why are Sunday newspaper circulations falling so sharply?

    The primary drivers are digital news consumption, the shift to social media for breaking stories, and a younger demographic that has never developed a habit of buying print. Rising production and distribution costs have also pushed cover prices up, which further reduces casual purchasing.

    Are Sunday newspapers moving online instead of closing?

    Most are pursuing digital subscription models alongside print. The Sunday Times has around 400,000 digital subscribers across its brands. The Observer has been restructuring towards a more digital-led operation. Print editions are likely to continue shrinking in frequency or size rather than vanishing overnight.

    Which British Sunday newspaper still has the best investigative journalism?

    The Sunday Times Insight team and the Observer are generally considered to produce the strongest original investigative work amongst the remaining Sunday titles. Both have broken significant stories in recent years, though their print supplements have also been cut back considerably compared to ten years ago.

  • Why Amateur Athletics in Britain Is Facing a Funding Crisis Just as Interest Peaks After Paris 2024

    Why Amateur Athletics in Britain Is Facing a Funding Crisis Just as Interest Peaks After Paris 2024

    There is a particular cruelty to the timing. Katarina Johnson-Thompson crossed the heptathlon runway in Paris to a British public suddenly gripped by athletics. Keely Hodgkinson won gold. Josh Kerr ran the race of his life. For a few weeks in the summer of 2024, people who had never previously cared about the 800 metres were genuinely invested. And now, in 2026, the clubs and coaches who should be capitalising on that wave of interest are instead cutting sessions, losing facilities, and watching junior programmes quietly fold. The uk athletics funding grassroots 2026 picture is, frankly, grim.

    Junior athletes training at a community track, illustrating the uk athletics funding grassroots 2026 challenge
    Photo by Mike Huang on Pexels

    What the cuts actually look like on the ground

    UK Athletics, the sport’s national governing body, has faced a sustained reduction in Sport England lottery funding over the past three years. The organisation itself has publicly acknowledged the pressure, and the effects have cascaded downward in ways that rarely make national headlines. Fewer development coaches. Reduced support for county athletics associations. Grant schemes for clubs that simply disappeared without replacement.

    I spoke to a coach at a mid-sized club in the East Midlands last month. She has been running the junior throws programme for eleven years. This year, for the first time, she is paying for shot puts and javelins out of her own pocket because the club’s small Sport England grant was not renewed. The club applied twice. Both times, the paperwork went in. Both times, nothing came back. She is still coaching, because she loves it. But she is clear-eyed about what happens when coaches like her eventually stop: there is nobody and nothing waiting to replace them.

    This is not an isolated case. The BBC’s athletics coverage has touched on the tension between elite success and grassroots neglect, though the full scale of the problem rarely gets the airtime it deserves. Field events in particular are being hollowed out. Pole vault, hammer, triple jump: these are disciplines that need specialist equipment, specialist coaching, and a facility willing to maintain a runway or a throwing cage. Strip the funding and the specialism dies within a generation.

    Why the post-Olympic bump is not translating into participation

    The pattern after major Games is fairly well established. Public interest spikes. Parents ring clubs asking about joining. Teenagers who watched the finals feel something stir. The question is always whether the infrastructure exists to catch that interest and convert it into long-term participation. Right now, in far too many parts of Britain, it does not.

    Running clubs have seen membership enquiries rise since Paris 2024. That part is real. But several clubs I am aware of have been turning people away, not because they are elitist or unwelcoming, but because they do not have enough coaches to safely run more sessions. The UK Coaching qualification pathway costs money and time. Without subsidised routes for volunteer coaches, clubs plateau at whatever size their current volunteer base can manage.

    The field events picture is worse. A youngster who wants to try the long jump or the discus after watching the Olympics needs a club with the right track and field setup. There are around 1,500 affiliated athletics clubs in England according to Sport England data, but the number with a full complement of throwing and jumping facilities is far smaller. Many community tracks are ageing infrastructure, owned by local councils who are themselves facing severe budget pressure. When a hammer cage corrodes or a high jump mat needs replacing, there is no automatic funding source to fix it.

    This connects to a broader pattern in British sport. You can see the same dynamic in cricket, where the ECB is wrestling with county-level engagement and participation problems that sit awkwardly alongside healthy elite revenues. The pipeline from watching to doing is never automatic. It requires investment.

    The Sport England lottery squeeze

    Sport England’s lottery income has been under pressure for several years. The national lottery generates less than it once did, and the funding pot is contested across a wide range of sports, arts organisations, and community projects. UK Athletics is competing for a shrinking resource, and the decisions about how to allocate what remains are difficult. Prioritising Paralympic and Olympic medal pathways is defensible in isolation. But when it comes at the cost of the grassroots development that eventually feeds those pathways, the logic starts to eat itself.

    My reading of the figures is that the governing body has been in an impossible position: protect elite performance funding to maintain the medal haul that justifies its public profile, while the club-level infrastructure quietly degrades beneath it. Neither choice is comfortable. But it is the club coaches and junior athletes who are absorbing the consequence.

    There is also a geography problem. Funding tends to follow existing strength. Clubs in areas with established athletics traditions and good facilities are better placed to write competitive grant applications, maintain relationships with county associations, and attract the kind of volunteer base that keeps a club functioning. Clubs in post-industrial towns or coastal communities, where athletics infrastructure was already thin, are the ones going under quietly.

    What needs to change if the sport is serious about growth

    The honest answer is that UK athletics funding at grassroots level in 2026 needs a structural rethink, not another year of patching. A few things stand out as genuinely useful: a ring-fenced development fund for field event equipment, accessible without the bureaucratic burden that has put off smaller clubs; a subsidised coaching qualification route specifically for volunteer club coaches; and a realistic audit of which community athletics tracks are close to the point of no return and need capital investment now.

    None of that is cheap. But the alternative is watching the post-Paris enthusiasm drain away into nothing, exactly as happened after London 2012, exactly as it risks happening again. I covered that 2012 legacy story with a degree of optimism at the time. Fourteen years later, the evidence that Olympic cycles actually drive sustained grassroots participation is mixed at best, and the current funding environment makes a repeat performance look even less likely.

    The broader lesson here is one British sport keeps having to relearn. Elite success and grassroots health are not the same thing. The Premier League generates billions, and yet ordinary fans are increasingly priced out of attending matches. Women’s football is breaking attendance records whilst Women’s Super League matches remain hard to find on free-to-air television. Athletics is not unique in struggling to connect its shining elite window with the messy, expensive, volunteer-dependent reality at club level. But it is running out of time to fix the gap.

    The coaches and club secretaries doing this work deserve better than an administration scrambling to balance its books. And the kids who watched Keely Hodgkinson win gold and thought, maybe I could try that, deserve a sport capable of saying yes.

  • Why Premier League Ticket Prices Are Pricing Out Ordinary Fans in 2026

    Why Premier League Ticket Prices Are Pricing Out Ordinary Fans in 2026

    There was a time when going to the match meant scrimping together a few quid, squeezing onto a terrace, and spending the afternoon shoulder to shoulder with people from the same street as you. That version of football exists in memory and in nostalgia, but the numbers tell a grimmer story for 2026. Premier League ticket prices have reached a point where attending a home fixture regularly is, for many working families, simply not affordable. I’ve spoken to fans from clubs across England for this piece, and the picture is pretty consistent wherever you look.

    Packed football stadium crowd illustrating the debate over Premier League ticket prices
    Photo by Luis Quintero on Pexels

    What top-flight tickets actually cost right now

    The average Premier League match ticket for the 2025/26 season sits at around £55 for a category A fixture, according to the BBC Sport coverage of fan group surveys. But that figure flatters the reality. At Arsenal, the most expensive single-match adult ticket for a high-demand fixture reaches £97. Manchester City’s top bracket sits at £85. Chelsea charge up to £75 for category A matches at Stamford Bridge. Add a train to London from the Midlands, a pie and a pint (where still available inside grounds), and a family of four is looking at well over £350 for a single afternoon out.

    Season tickets offer better value per game, but the upfront cost is its own barrier. At Newcastle United, a season ticket in a decent area of St James’ Park now starts at around £575 and rises sharply. Liverpool’s cheapest adult season ticket is roughly £685. For a household where two adults work in the public sector or on minimum wage, that is a month’s salary, gone on football.

    Which clubs have raised prices the most since 2019

    The pandemic masked what might have happened organically. When fans returned to grounds in 2021, several clubs held prices. That goodwill has largely dissolved. Since 2019, the average top-division ticket has risen by around 18 to 22 per cent in real terms, outpacing wage growth for most of the occupational groups that historically made up the terraces. The clubs that have pushed hardest include those with high demand and limited capacity, where supply and demand logic takes over from any sense of community obligation.

    It is worth noting that some clubs have bucked this. Brighton and Hove Albion froze away ticket prices for travelling supporters across several seasons, and Brentford made real efforts to keep their general admission prices accessible while making the transition to the top flight. These are the exceptions. The broader direction of travel is upward.

    Football ground turnstile representing the cost barrier of Premier League ticket prices
    Photo by Liliana Drew on Pexels

    The away supporter problem

    Away fans have their own crisis. The Premier League’s away ticket cap, introduced in 2022 and set at £30 per adult, was widely praised. It remains in place. The trouble is that the cap covers only a fraction of the real cost. Travel to an away fixture at a club like Tottenham or Everton from somewhere like Sunderland or Sheffield means train fares that, booked late or on a weekend, can exceed £100 per person. Factor in that away allocations are shrinking at several grounds due to stadium redevelopments, and the away end culture that has historically been one of football’s loudest and most passionate spaces is under genuine threat.

    Fan groups have been increasingly vocal about this. Organisations tracking supporter welfare argue that the matchday experience is no longer designed around the kind of fan who built these clubs. Groups working on activism.digital and similar platforms have documented how local campaigns around ticket pricing have grown markedly since 2023, reflecting a real mood shift among supporter bases who feel ignored by club boardrooms.

    What this means for working-class communities

    Football in England did not grow out of the middle classes. The sport was built in mill towns, mining communities, and industrial cities. The cultural identity of clubs like Burnley, West Ham, Wolves, and many others is inseparable from those working-class roots. What is happening now is a slow but unmistakable demographic shift in the stands. Hospitality packages, premium seating, and corporate boxes generate far more revenue per head than a standard adult ticket, and clubs know it. The incentive to fill a ground with wealthier supporters is purely financial.

    I’d argue this is not a marginal concern. When working-class fans are priced out over a decade, the noise, the atmosphere, the connection between club and place changes. Grounds become quieter, more polite, occasionally eerie. Some long-term supporters at top-six clubs I’ve spoken to describe a feeling of being tourists in their own stadium.

    This connects to a broader pattern of rising costs squeezing people out of things they used to take for granted. We covered something similar in our piece on Women’s Super League matches and the difficulty of finding them on free-to-air television, where access to the game, whether through a gate or a screen, keeps narrowing for ordinary people. And in a totally different domain, the same logic applies to pieces like our look at Britain’s housing benefit gap, where the gap between what things cost and what working people can actually afford keeps widening.

    Is there any pressure on clubs to change course

    The Premier League as a body has resisted setting a general ticket price cap beyond the away-fan measure. There have been calls from MPs, from the Football Supporters’ Association, and from within clubs’ own supporter trusts for something more structural. The government’s Football Governance Bill, which made progress through Parliament in 2025, includes provisions around fan representation on club boards, which could in theory give supporter voices more weight in pricing decisions. Whether that translates into cheaper tickets in practice remains to be seen.

    Some clubs point to financial pressures of their own: wage bills, stadium debt, infrastructure projects. These are real. But when the Premier League distributed £2.8 billion in television money across the top flight for 2024/25, it is hard to sustain the argument that the league cannot afford to look after the fans who fill seats, generate atmosphere, and made the product attractive enough to sell globally in the first place.

    My reading of where this ends up: without a binding price structure that protects a portion of tickets at genuinely accessible rates, the drift will continue. The clubs with the most demand have the least incentive to act voluntarily. Meaningful change is more likely to come from regulation than from goodwill. And the longer it takes, the more the character of the matchday crowd shifts permanently away from the communities these clubs came from.

    Frequently Asked Questions

    What is the average Premier League ticket price in 2026?

    For a category A fixture, prices across Premier League clubs average around £55 for an adult walk-up ticket, but top clubs like Arsenal charge close to £97 for high-demand matches. Season tickets range from roughly £575 to well over £1,000 depending on the club and seat location.

    Is there a Premier League ticket price cap for away fans?

    Yes. The Premier League introduced a £30 cap on away tickets for adult supporters, which remains in place for the 2025/26 season. However, this does not cover travel costs, which can easily add £80 to £120 per person for longer journeys.

    Which Premier League clubs have the cheapest season tickets?

    Clubs like Brentford and Brighton have made efforts to keep standard adult season tickets below the top-division average. Exact prices shift each season, so checking club websites directly is the most reliable approach. The Football Supporters’ Association also publishes annual price comparison data.

    Why are Premier League ticket prices rising faster than wages?

    Clubs generate significantly more revenue per seat from premium and hospitality packages than from standard tickets, creating a financial incentive to shift their pricing mix upward. High demand for limited seat capacity at top clubs also gives them room to raise prices without reducing attendance.

    Can anything be done to lower Premier League ticket prices?

    The Football Governance Bill passing through Parliament includes measures on fan representation in club decision-making, which could influence pricing policies. Many supporter groups and the Football Supporters’ Association are pushing for a mandatory affordable ticket allocation at each club, similar to rules that exist in the Bundesliga in Germany.

  • Women’s Super League Crowds Are Breaking Records, So Why Are Most Matches Still Hard to Find on Free-to-Air TV?

    Women’s Super League Crowds Are Breaking Records, So Why Are Most Matches Still Hard to Find on Free-to-Air TV?

    Chelsea versus Arsenal at Kingsmeadow pulled over 5,000 fans last season. Manchester City’s home fixtures at the Academy Stadium regularly sell out. The WSL’s average attendance has risen for four consecutive seasons, and the FA confirmed in early 2026 that cumulative live crowds across the league had hit an all-time high. Good news, clearly. But try watching those matches without a Sky Sports or BBC iPlayer subscription, and you’ll quickly discover the uncomfortable truth about womens super league tv rights uk: most of the action is locked behind a paywall, or simply not televised at all.

    Packed stadium crowd at a WSL match reflecting the womens super league tv rights uk debate
    Photo by Franco Monsalvo on Pexels

    I’ve followed women’s football since the early days of the league’s rebrand, back when crowds of a few hundred was normal at top-flight grounds. The growth since then has been extraordinary. But the broadcasting picture hasn’t kept pace, and with the current rights deal approaching renewal, the gap between the sport’s popularity and its accessibility is becoming harder to ignore.

    Where you can actually watch WSL matches right now

    The current arrangement splits rights between Sky Sports, which holds the lion’s share of live fixtures, and the BBC, which shows a more limited number of games across BBC Two and BBC iPlayer. Channel 4 had previously made noise about entering the women’s football rights space, and it did air some coverage during the Euros, but the WSL itself remained outside its portfolio. ESPN UK has also carried some matches for subscribers. The upshot is that a casual fan, someone who doesn’t have a Sky package and isn’t methodically checking iPlayer schedules, will miss the overwhelming majority of WSL action in a given season. According to BBC Sport, the corporation streams selected WSL matches, but the volume is a fraction of what Sky broadcasts across its dedicated women’s football coverage.

    For context: the men’s Premier League operates on a similar mixed model, but the sheer volume of mainstream media coverage, highlights packages on Match of the Day, and cultural ubiquity means casual fans rarely feel cut off. Women’s football doesn’t have that safety net yet. If a match isn’t on free-to-air, it largely doesn’t happen for most of the country.

    What campaigners are pushing for ahead of the next rights deal

    Campaign groups including Women’s Sport Trust have been consistent in their argument that the WSL should be placed on the UK’s list of protected sporting events, ensuring certain matches must be shown free-to-air. That list, maintained under the Broadcasting Act 1996 and periodically reviewed by the government and Ofcom, currently covers events like Wimbledon, the FA Cup final, and the Olympics. The WSL is not on it.

    The argument isn’t anti-Sky, or anti-subscription broadcasting in general. The argument is that the sport is still building its audience, and that audience growth is disproportionately dependent on visibility. Research published by Women’s Sport Trust in 2025 found that casual female sports viewers are significantly more likely to engage with a sport when they encounter it by chance on free-to-air television. That “stumble upon” effect is almost impossible to replicate behind a paywall. You don’t accidentally find a match you weren’t looking for when you’re scrolling a subscription menu.

    My reading of the figures is that the WSL has done almost everything right on the pitch and in the stands. The product is better. The players are better known. Young girls actually have footballers to name when you ask them. The broadcasting model is the weak link.

    The rights deal money question

    This is where it gets complicated. Sky’s investment isn’t just about broadcasting matches. It funds the league. The current deal was reportedly worth around £8 million per season across all rights holders, a figure that sounds modest against Premier League sums but represented a genuine step up for a league that had previously operated on far thinner margins. Any shift to free-to-air carries a financial risk that clubs are aware of. A Channel 4 or ITV deal would broaden reach, but it might not match the commercial value Sky brings.

    The upcoming rights negotiation, expected to conclude in late 2026 for a deal beginning in the 2027-28 season, will test whether the Football Association and WSL clubs prioritise growth or revenue. The honest answer is they’ll try to do both, probably through a tiered model where some matches go to a free-to-air partner and Sky retains the premium package. Whether that’s enough for campaigners is a different question.

    For what it’s worth, I think a model closer to how cricket handled The Hundred, with Channel 4 carrying highlights and a meaningful number of live fixtures, would be a reasonable middle ground. The sport gets exposure; Sky keeps its premium content. Whether the economics actually allow that is something only the negotiating parties know.

    What the crowd numbers tell us about untapped demand

    Record attendances while most matches aren’t easily visible on television is a striking combination. It suggests the in-person audience is growing organically, driven by community investment, lower ticket prices relative to men’s football, and genuine enthusiasm for the game. But it also suggests the broadcast audience is still underserving the potential. If people are filling grounds without heavy TV promotion, imagine what broad free-to-air exposure might do.

    The comparison to county cricket is instructive. English county cricket has struggled for years to translate its committed niche following into broader public interest, partly because it disappeared behind subscription television before the audience had fully formed. That attendance problem is well documented, and women’s football campaigners are clearly aware of the cautionary tale. They want the WSL to lock in mass-market visibility before the subscription model becomes its permanent home.

    The British cycling boom offers a slightly more optimistic comparison. Grassroots participation grew sharply on the back of free-to-air Tour de France and Olympic coverage, and that momentum sustained itself even as some elite cycling moved behind paywalls. The lesson there is that early free-to-air exposure builds a bedrock of engaged fans who’ll follow the sport wherever it goes. Women’s football has that window now. Whether the rights deal takes advantage of it is the central question of the next 18 months.

    What needs to happen before the deal is signed

    Ofcom has the power to expand the protected events list, and there is a legitimate public interest case for including at least the WSL final and selected England women’s domestic fixtures. A number of MPs, particularly on the Culture, Media and Sport Select Committee, have raised the issue explicitly. The government’s position has been cautiously sympathetic without making concrete commitments.

    The FA, to its credit, has consistently said it wants to grow the women’s game’s visibility. Whether that stated priority survives contact with an attractive Sky bid will tell us everything about how seriously the growth agenda is actually taken. My expectation is a compromise. A free-to-air partner for a portion of fixtures, Sky retaining the bulk. Whether that’s enough is genuinely unclear. But the pressure from fans, campaign groups, and parliamentarians is at a level that means the next deal will be scrutinised in a way the current one simply wasn’t.

    Women’s football deserves to be found easily by people who haven’t yet realised they want to watch it. That’s the whole argument, really. And with a rights deal on the horizon, there’s a real chance to get this right.

    Frequently Asked Questions

    Where can I watch WSL matches on free-to-air TV in the UK?

    The BBC shows a selection of WSL matches on BBC Two and via BBC iPlayer, but the majority of live fixtures are on Sky Sports. The number of free-to-air games available in a season is limited, meaning casual viewers miss most of the action without a subscription.

    When does the next WSL TV rights deal start?

    The current rights arrangement is expected to be renegotiated with a new deal beginning from the 2027-28 season. Negotiations are anticipated to conclude during 2026, making this a significant period for anyone campaigning for improved free-to-air coverage.

    Is the WSL on the UK's list of protected sporting events?

    No. The protected list under the Broadcasting Act 1996, which mandates free-to-air coverage for certain events, does not currently include any WSL fixtures. Campaign groups have been lobbying for at least the WSL final to be added ahead of the next rights deal.

    How much is the WSL TV rights deal worth?

    The current deal across all rights holders was reported to be worth approximately £8 million per season, a meaningful increase on earlier arrangements but still modest compared to top-tier men’s football rights. The next deal is expected to attract higher bids given the sport’s growing attendances.

  • Britain’s Rivers Are in Crisis: What the Latest Water Quality Data Means for Swimmers and Anglers

    Britain’s Rivers Are in Crisis: What the Latest Water Quality Data Means for Swimmers and Anglers

    England’s rivers are struggling. That is the blunt conclusion you reach after working through the Environment Agency’s most recent assessments of UK river water quality in 2026, and the picture they paint is not a comfortable one. According to the Agency’s own figures, not a single river in England currently meets the standard for good ecological and chemical status under the Water Framework Directive. Not one. I’ve been following this story for a few years now, and even I found that number startling when I saw it restated so plainly in the latest data.

    For millions of people who fish, swim, or simply walk along riverbanks, this matters far beyond the abstract. Wild swimming has grown enormously as a pastime over the past decade, with groups like the Outdoor Swimming Society reporting surging membership. Angling clubs across the country, already dealing with falling stocks in some stretches, are watching their rivers worsen season by season. The question is: what is actually going wrong, and is anyone fixing it?

    Peaceful English river scene reflecting the wider concerns around uk river water quality 2026
    Photo by Jan Wright on Pexels

    What the Environment Agency data actually shows

    The Environment Agency publishes regular assessments of river health, covering biological indicators such as fish populations, invertebrate counts, and plant life, alongside chemical measurements for pollutants including phosphorus, nitrates, and sediment. You can read the headline findings directly on the gov.uk water framework reporting pages. The pattern is consistent: agricultural run-off, sewage overflows, and urban drainage are the three main culprits pulling rivers below acceptable standards across England.

    Sewage discharges have received the most press attention, and rightly so. Water companies released sewage into English rivers and waterways for a combined total running into millions of hours annually in recent years, with Yorkshire Water, Anglian Water, and Thames Water among the worst offenders named in Environment Agency enforcement reports. Phosphorus loads from agriculture remain persistently high across the Midlands and East Anglia. Chemical contamination from roads and car parks washes into river systems every time it rains hard, contributing to what ecologists call “urban runoff cocktails” that are difficult to regulate and near-impossible to reverse quickly.

    Why wild swimmers face the biggest immediate risk

    Wild swimming carries a real and specific set of risks when river water quality is poor. Bacteria such as E. coli and Cryptosporidium, both associated with untreated sewage, can cause serious gastroenterinal illness within 24 to 48 hours of exposure. Blue-green algae blooms, triggered by warm temperatures and high nutrient loads, produce toxins that can affect the liver and nervous system. The Kennet in Berkshire, the Wye along the England-Wales border, and stretches of the Trent through the East Midlands have all featured in recent warnings issued by the Environment Agency and local councils.

    This is where the household angle connects to the wider crisis. The same bacteria and germs that make rivers unsafe for swimming are a genuine concern in everyday domestic settings too. Homeowners in Nottinghamshire and beyond have grown more conscious of bacterial contamination in and around the house, which is why specialist cleaning services have expanded considerably. The Bin Boss, a Nottinghamshire-based wheelie bin cleaning service specialising in the removal of bacteria, germs, and odour-causing organisms from domestic bins, has seen this awareness translate directly into demand. The connection is straightforward: when the public understands what bacteria actually does to an environment, whether a river or the area around your house, the appetite for proper cleaning grows. Their site at thebinboss.co.uk makes the case plainly: bins left uncleaned harbour the same categories of harmful bacteria that water quality reports warn about.

    Back on the rivers, the practical advice from the Environment Agency and the wild swimming community is consistent. Check the Swimfo bathing water designation for your chosen spot before entering. After any rainfall in the preceding 48 hours, assume water quality has dropped. Avoid areas directly downstream of farms, sewage treatment works, or where you can see discolouration or foam on the surface.

    Foam and algae on a UK river surface highlighting poor uk river water quality 2026
    Photo by Engin Akyurt on Pexels

    What this means for anglers

    Anglers face a different but equally serious set of problems. Fish kills, caused by oxygen depletion or direct toxic discharges, have been recorded across dozens of rivers in England in the past three years. The Angling Trust, which represents over a million anglers in England, has been vocal in pushing the Environment Agency for more enforcement action against polluters. Their frustration is understandable: the legal framework exists to prosecute serious polluters, but the Agency’s enforcement budget has been cut repeatedly over the past decade, reducing the number of inspections and follow-up actions it can realistically carry out.

    Salmon and sea trout runs have collapsed on several southern chalk streams that were once internationally respected. The Test, the Itchen, and the Avon have all seen population crashes that fishing guides and Environment Agency scientists now attribute to a combination of over-abstraction, agricultural nitrate loading, and reduced water flow during summer months exacerbated by climate patterns. Brown trout fishing on many upland rivers remains somewhat healthier, particularly in the north of England and parts of Wales, but even there the trends are not encouraging.

    For coarse anglers, the picture is mixed. Carp and bream tolerate poor water quality better than salmonids, but roach, dace, and gudgeon populations have dropped sharply in rivers where silt accumulation has smothered the gravel beds they spawn on. The Environment Agency’s own fish survey data shows the trend clearly: species diversity is falling even where overall biomass appears stable.

    Who is pushing back and what are they asking for?

    Pressure on water companies and the government has intensified considerably. The Angling Trust and Surfers Against Sewage have both run high-profile campaigns, and parliamentary committees have grilled water company executives on their sewage overflow records. The Water (Special Measures) Act, which received Royal Assent in early 2025, introduced tougher penalties for water companies and new duties to monitor and report discharges in real time.

    Whether that translates into actual improvement in UK river water quality in 2026 and beyond depends largely on enforcement and investment. Water companies have committed to multi-billion pound infrastructure programmes, but the timescales stretch well into the 2030s. In the meantime, swimmers and anglers are left navigating a system where the rules are tightening but the water itself is not yet getting cleaner at any meaningful pace.

    The Environment Agency has also flagged the role of individual households and small businesses in contributing to river pollution through incorrect disposal of cooking oil, wet wipes, and household chemicals. That framing puts some responsibility at the domestic level, which is fair. Bins left uncleaned and overfull with waste that contains bacteria and organic material can end up contributing to surface run-off in extreme weather. Services like The Bin Boss, which targets bacterial build-up in wheelie bins as a specific cleaning and hygiene problem for homes across Nottinghamshire, sit within a broader ecosystem of cleanliness that, scaled up, has genuine environmental relevance.

    What you can do right now

    If you fish or swim, the most practical step is to use the Environment Agency’s real-time water quality tools and sign up for alerts from your local river trust. The gov.uk bathing water quality pages are updated regularly and cover designated bathing spots. For non-designated stretches, the Outdoor Swimming Society maintains a community-reported map that is genuinely useful.

    For anglers who witness a fish kill or suspected pollution incident, report it immediately to the Environment Agency’s 24-hour hotline on 0800 807 060. Speed matters: the earlier an incident is logged, the higher the chance of identifying the source and securing evidence for prosecution.

    There is no quick fix for England’s rivers. The scale of the infrastructure problem, combined with the pace at which agricultural practices are changing, means that a genuinely clean river network is probably a generation away. That is a grim conclusion, but it is also an honest one. If you are interested in how the environment around your home connects to these broader issues, our article on storm preparation for British homes covers surface water flooding and drainage, which feeds directly into river pollution events. And if the wider picture of how the British outdoor environment is being used and enjoyed interests you, the piece on the British cycling boom touches on how communities are pushing back and reclaiming green and blue spaces despite the pressures they face. For gardeners concerned about what poor water quality means for irrigation and soil health, our guide to composting in a small British garden offers some grounded, practical alternatives to water-intensive growing methods.

  • The Decline of the British High Street Bookshop and What Is Actually Replacing It

    The Decline of the British High Street Bookshop and What Is Actually Replacing It

    The story of british high street bookshops in 2026 is not the simple obituary many predicted. Yes, WHSmith is pulling down the shutters on its retail division. Yes, footfall across British town centres has been uneven since the pandemic scrambled shopping habits. But walk through Hebden Bridge, Hay-on-Wye, or even a mid-sized market town like Shrewsbury on a Saturday morning, and something unexpected is happening: people are queuing outside independent bookshops. Not metaphorically. Literally queuing.

    I’ve been watching this space for a while now, and the picture is genuinely more complicated than either the doom-mongers or the cheerleaders want to admit. There are real casualties, real survivors, and some genuinely odd new shapes that British book retail is taking.

    Independent bookshop on a British high street, part of the british high street bookshops 2026 story
    Photo by Budgeron Bach on Pexels

    WHSmith’s retail retreat and what it actually means

    Let’s start with the most dramatic development. WHSmith confirmed in early 2026 that it would be winding down its high street retail arm, redirecting all focus to its travel-hub business: airport terminals, railway stations, hospitals. The BBC’s business desk has covered the slow erosion of WHSmith’s high street presence for years, but the formal exit still landed with a thud.

    WHSmith was never really a bookshop. Walk into any branch in recent years and you’d find stationery, snacks, overpriced water, and a small paperback section that felt like an afterthought. The books were there, but no one was curating them. The point was margin, not love of literature. So in one sense, the closure of those outlets is not the death of book retail. It’s the death of a model that was never particularly good at selling books anyway.

    What it does mean, practically, is that dozens of town centres now have large vacant units where WHSmith used to sit. In some places, that’s already being treated as an opportunity. A few local councils are actively recruiting independent retailers, including bookshops, to fill those spaces on subsidised short-term leases. Whether that momentum holds depends almost entirely on local authority budgets, which are under the usual pressure.

    Waterstones: steadier than you might think

    Waterstones, which has been owned by Elliott Advisors since 2018, has quietly had a decent run. The chain closed some underperforming branches in 2024 and 2025 but held firm in most major city centres and university towns. Its model leans heavily on staff recommendation, local knowledge, and events. The Waterstones in Piccadilly remains one of the most visited bookshops in Europe. That’s not a fluke; it’s the result of treating the physical space as an experience rather than a warehouse.

    What Waterstones figured out, arguably before most British retailers did, is that a bookshop has to give you something a screen cannot. Author events, signed editions, a café table where you can sit and read the first chapter before deciding. These things sound small, but they are the difference between a shop that competes with Amazon and one that doesn’t try to.

    The indie bookshop comeback that nobody fully planned

    Here is the number that keeps catching people off guard. According to the Booksellers Association, the number of independent bookshops in the UK has grown from around 900 in 2016 to over 1,100 by the mid-2020s. That is a counter-intuitive trend given everything else happening on the high street.

    Part of the explanation is rent. Commercial property rates in secondary towns and smaller high streets collapsed hard during 2020-2022, and they haven’t fully recovered. That created an opening for people with a real passion for books and a modest amount of capital to take on affordable leases. Some of these shops are tiny, 400 square feet with a cat asleep in the window, but they’re trading.

    The other part is community. I spoke to the owner of an independent shop in a Midlands market town last autumn who told me her Saturday events, a mix of children’s reading groups and local author talks, were regularly pulling 40 to 60 people through the door. That’s 40 to 60 people who walked past every other retail unit to get there. A bookshop that hosts events becomes a community venue, and community venues are surprisingly resilient.

    This connects to a broader point about what’s actually reviving some British town centres. It’s not the return of big chains. It’s the clustering of independent, experience-led businesses: a deli, a bookshop, a small brewery taproom, an art gallery. Individually fragile; together, they create a reason to visit. The high street as destination rather than convenience hub is a model that seems to be holding in places where local councils and landlords have been flexible enough to let it develop. You can see a parallel dynamic in how some outdoor and lifestyle businesses have adapted too, something I’ve noticed covering the British cycling boom and the way experience-based retail has followed that wave.

    Online, physical, or somewhere in between?

    The binary of online versus physical retail has always been slightly false, and nowhere is that clearer than books. Hive.co.uk, which channels online sales through independent bookshops rather than Amazon, has grown steadily. Bookshop.org launched its UK version in 2021 and has distributed millions of pounds to independent shops through its affiliate model. These platforms didn’t kill the physical shops; they became feeders for them.

    At the same time, audiobooks and ebooks continue to grow, particularly amongst commuters and people managing busy households. The Publishers Association’s most recent figures show physical book sales in the UK remain strong, particularly in children’s and literary fiction, but the overall market is genuinely multiformat now. A bookshop owner who ignores digital isn’t necessarily doomed, but one who pretends it doesn’t exist is probably in trouble.

    What happens to the towns that lose their last bookshop?

    Not every story here is optimistic. Plenty of smaller towns have no bookshop at all, and the closure of the local WHSmith branch has left them with nothing. Libraries, already reduced by years of council funding cuts, are often the only place to borrow or browse a physical book. The same pressures battering local print media apply here: when the economics of serving a small community don’t add up, the market exits, and what’s left is a cultural gap.

    There’s also a question of what gets stocked. Independent bookshops tend to champion local authors and literary fiction. WHSmith tended to push bestseller lists and promotional titles from major publishers. Neither model is perfect, but the variety between them served different readers. Losing one type of outlet doesn’t just reduce choice; it changes whose books get discovered.

    My read of british high street bookshops in 2026 is this: the sector is not dying, but it is sorting itself into two distinct worlds. Towns with engaged communities, affordable property, and a bit of local authority imagination are seeing genuine revival. Towns without those ingredients are seeing shelves go bare. The difference isn’t the internet. It’s whether anyone with power locally has decided that books, and the kind of street life that forms around them, are worth fighting for. Much like planning decisions shaping what gets built in neighbourhoods, the future of the bookshop is, in the end, a local political choice as much as a retail one.

    Frequently Asked Questions

    Is WHSmith closing all its high street shops in 2026?

    WHSmith announced in 2026 that it is winding down its high street retail division to focus exclusively on its travel-hub outlets in airports, railway stations, and hospitals. The full closure timeline for individual branches varies, but the direction is clear: the traditional town centre WHSmith is finished.

    Are independent bookshops in the UK growing or declining?

    Independent bookshops have actually grown in number since the mid-2010s. The Booksellers Association tracked a rise from around 900 shops in 2016 to over 1,100 by the mid-2020s, driven partly by lower commercial rents in secondary towns and a growing appetite for community-focused retail experiences.

    How is Waterstones performing in 2026?

    Waterstones has closed some underperforming branches in recent years but remains stable in major city centres and university towns. Its focus on staff-curated recommendations, author events, and signed editions has helped it hold ground against online competition in a way pure volume-led retail could not.

    Can I buy from independent bookshops online rather than using Amazon?

    Yes. Platforms like Bookshop.org UK and Hive.co.uk allow you to order online while directing revenue to independent bookshops rather than large retailers. Bookshop.org in particular distributes a share of every sale to indie shops through an affiliate model.

    Why are some British town centres seeing a bookshop revival?

    Lower commercial rents, community demand for experience-led retail, and local authority schemes offering subsidised short-term leases have all contributed. Bookshops that host events, reading groups, and author talks function as community venues, which makes them stickier than a standard retail unit selling only off the shelf.